decoration tips decoradhouse from decoratoradvice, start writing letsbuildup.org blog, which diagram shows lines that must be parallel lines cut by a transversal?, best tech news feedcryptobuzz, dreamwithjeff com, start wizzydigital.org blog, about blog wizzydigital.org, why interior design is interesting mintpaldecor, how was teckaya construction equipment founded

How Big Is 150 Square Feet? A Complete Guide

When I first heard someone mention a “150-square-foot room,” I’ll admit — I had no real sense of how big that actually was. Was it tiny, like a walk-in closet, or big enough for a full bedroom setup?

If you’re asking how big is 150 square feet, you’re not alone. It’s a question that comes up often when people are designing rooms, renting apartments, buying storage units, or even planning office layouts.

In this guide, I’ll break it all down in plain language. We’ll explore what 150 square feet looks like in real life, what fits inside, how it compares to other room sizes, and how to make the most of every inch.

What Does 150 Square Feet Look Like?

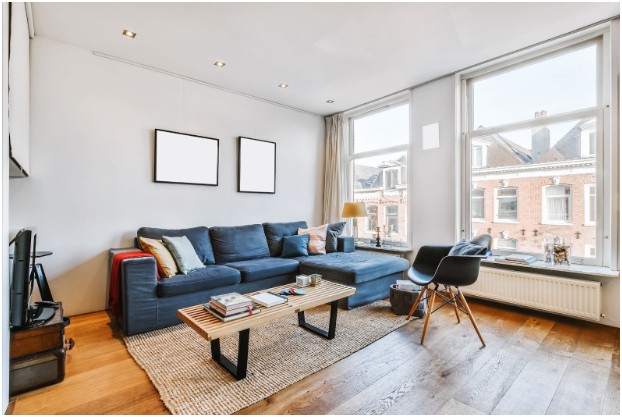
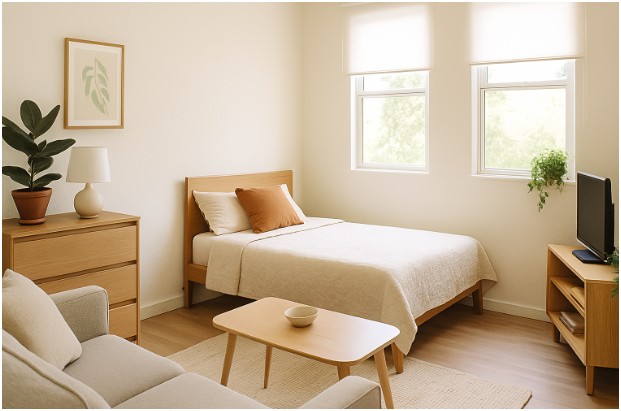
To visualize how big 150 square feet is, it helps to think in terms of actual dimensions. A 150-square-foot room is usually about 10 feet by 15 feet. That’s roughly the size of a standard guest bedroom or a small one-car garage.

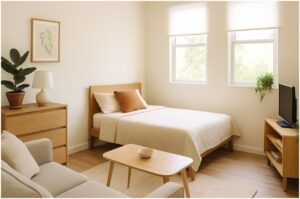
Here’s another way to picture it: stand in a small bedroom with enough space for a queen bed, a dresser, and a nightstand — that’s about 150 square feet.

It’s not massive, but it’s far from cramped. It’s a sweet spot for many uses because it offers flexibility without overwhelming space.

Common Uses for a 150-Square-Foot Space
Common Uses for a 150-Square-Foot Space

A room of this size is surprisingly versatile. Here are some real-world examples to give you a better sense of its potential:

  • Guest Bedroom or Secondary Bedroom: This is one of the most common uses. You can fit a queen or king-sized bed, two nightstands, and a dresser comfortably. 
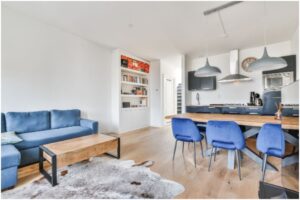
  • Small Studio Apartment: In urban areas, 150 square feet might serve as the main living space in a micro-apartment. With clever furniture choices, it can hold a sofa, a small table, and a bed. 
  • One-Car Garage Equivalent: Many single-car garages are close to this size, showing how much storage space you’d have for larger items. 
  • Storage Unit: A 10×15 storage unit is typically used to store the contents of a one- or two-bedroom apartment during a move. 
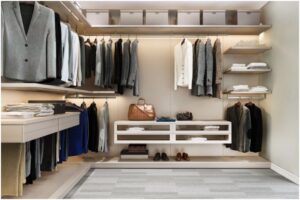
  • Walk-In Closet: In some homes, a luxury walk-in closet can be around 150 square feet — enough for wardrobes, shelving, and a dressing area. 
  • Small Office or Classroom: In a commercial setting, 150 square feet can accommodate a small office setup or even a compact classroom for a few students. 

What Can Fit in 150 Square Feet?

To get a more practical sense of how big 150 square feet is, let’s talk about what you can actually fit inside. This space can hold most essentials of a small apartment or room setup without feeling overcrowded.

Here’s a breakdown of what fits comfortably:

  • Bedroom Furniture: A queen or king bed, dresser, and two nightstands with space to walk around. 
  • Living Room Setup: A sofa, coffee table, TV stand, and shelving unit. 
  • Appliances: A refrigerator, washer, and dryer can fit if used as a laundry or storage area. 
  • Storage Boxes: Many moving boxes can be stacked efficiently with space left to create a small aisle for access. 
  • Outdoor Gear: Items like patio furniture, bicycles, and sports equipment can be stored without cluttering the space. 

With careful planning, 150 square feet can serve multiple purposes — even combining storage and functional living space.

Visualizing 150 Square Feet in Different Contexts
Visualizing 150 Square Feet in Different Contexts

It’s easier to understand a size when you compare it to spaces you already know. Here are a few real-world equivalents of 150 square feet:

  • A Large Walk-In Closet: Spacious enough for shelving, racks, and a dressing area. 
  • A Compact Studio Apartment: Many micro-apartments, especially in cities like New York or Tokyo, are around this size. 
  • A Small Office or Classroom: Enough space for a few desks and chairs. 
  • A Storage Unit: A 10×15 unit is common for people moving from a small home or apartment. 

Each of these examples shows how flexible 150 square feet can be — whether for living, working, or storing belongings.

Conversion to Other Measurements

If you’re working with metric units or thinking in terms of volume, here are some useful conversions for 150 square feet:

  • Square Meters: Approximately 13.94 square meters 
  • Cubic Feet (with 8-foot ceiling): About 1,200 cubic feet 

Understanding the volume helps if you’re planning storage, insulation, or HVAC needs, especially in construction or renovation projects.

Quick Comparison: 150 Sq Ft vs. Other Room Sizes

To put 150 square feet in context, here’s how it stacks up against other common room sizes:

Room Size (sq ft) Dimensions (approx.) Common Use Space Feeling
100 sq ft 10 x 10 ft Small bedroom or office Cozy and compact
150 sq ft 10 x 15 ft Guest bedroom, storage unit Versatile and functional
200 sq ft 10 x 20 ft Master bedroom or small studio Spacious for one person
300 sq ft 15 x 20 ft Large studio or small living room Roomy and open

This comparison shows where 150 square feet fits in the spectrum — larger than a small office, smaller than a big studio, and ideal for flexible use.

Tips to Make the Most of a 150-Square-Foot Room
Tips to Make the Most of a 150-Square-Foot Room

Even though 150 square feet offers decent space, smart planning can make it feel bigger and more functional. Here’s how:

1. Choose Multi-Functional Furniture

Opt for pieces that serve more than one purpose. A sofa bed, storage ottoman, or foldable table helps save space and add versatility.

2. Go Vertical

Use wall-mounted shelves, tall bookcases, or hanging storage to maximize vertical space and free up floor area.

3. Keep Layout Open

Avoid bulky furniture and leave clear pathways to make the room feel more spacious and less cluttered.

4. Use Light Colors

Lighter shades on walls and furniture reflect light, making the space look and feel larger.

5. Plan Your Zones

Even in a small space, you can create distinct zones — for example, a sleeping area, a reading nook, or a workspace — to make the room more functional.

Why 150 Square Feet Might Be All You Need

People often assume they need hundreds of square feet to live or work comfortably, but that’s not always the case. A 150-square-foot room can offer all the essentials — comfort, storage, and usability — without wasting space.

In fact, many modern living trends, like minimalist design and tiny homes, thrive within this size range. With thoughtful design and furniture choices, you can transform 150 square feet into a cozy, efficient space that meets your needs perfectly.

Frequently Asked Questions (FAQs)

How big is 150 square feet compared to a bedroom?

A typical bedroom in many homes ranges from 120 to 150 square feet. A 150-square-foot room is large enough for a queen or king bed, nightstands, and a dresser while leaving space to walk around.

Can two people live in a 150-square-foot space?

Yes, but it requires efficient use of space. Many micro-apartments in urban areas are around this size and house one or two people comfortably with multifunctional furniture and clever storage.

How many cubic feet is a 150-square-foot room?

Assuming a standard 8-foot ceiling, the total volume is about 1,200 cubic feet (10 × 15 × 8). This is helpful when calculating heating, cooling, or storage needs.

What can I store in a 150-square-foot storage unit?

A 10×15 storage unit can typically hold the contents of a one- or two-bedroom apartment, including furniture, appliances, moving boxes, and outdoor gear.

Is 150 square feet enough for a home office?

Absolutely. It’s more than enough space for a desk, chair, storage shelves, and even a small meeting area. It can comfortably accommodate 2–3 workstations.

Wrapping It Up: 150 Square Feet Packs More Than You Think

So, how big is 150 square feet? It’s about the size of a 10 x 15-foot room — larger than you might imagine.

Whether you’re designing a guest bedroom, renting a storage unit, or setting up a home office, this amount of space offers surprising flexibility. It’s big enough to be functional, yet small enough to encourage creativity and efficiency.

In an era where smart use of space matters more than ever, 150 square feet proves that size isn’t everything — how you use it is what truly counts.
More From Author

how old do you have to be to rent an apartment

How Old Do You Have to Be to Rent an Apartment?

how big is 250 square feet

How Big Is 250 Square Feet? Visualizing and Using Small Spaces

How Old Do You Have to Be to Rent an Apartment?

Finding your first place to live is exciting — a milestone of independence that often marks the transition into adulthood.

But before you start scrolling through listings and picturing how you’ll decorate your new space, there’s one practical question you need answered: how old do you have to be to rent an apartment?

The short answer is simple: in most places, you must be at least 18 years old to legally rent an apartment. That’s because a lease is a binding legal contract, and minors generally can’t enter such agreements on their own.

But the full story involves more than just age — things like income, credit history, and co-signers often play just as big a role.

Why Age Matters When Renting an Apartment

The age requirement to rent isn’t set by landlords — it’s based on contract law. In most countries, and across all U.S. states, 18 is the legal age of adulthood. That means you can sign contracts, make financial commitments, and be held legally responsible for the terms you agree to.

A lease is exactly that: a legal agreement between you (the tenant) and the property owner (the landlord). It spells out your rights and responsibilities, from how much rent you’ll pay and when, to how the property must be maintained.

Because minors typically can’t be held legally responsible for contracts they sign, landlords require tenants to be 18 or older.

What Happens If You’re Under 18?

What Happens If You’re Under 18?

If you’re younger than 18 and eager to move out — maybe for college, work, or personal reasons — don’t worry. Renting isn’t off the table entirely. You’ll just need someone legally able to sign the lease with you.

Here’s how that usually works:

  • Guarantor or co-signer: A parent, guardian, or another trusted adult can sign the lease alongside you. They’ll be legally responsible for the rent and any damages if you fail to meet your obligations.
  • Subletting: In some cases, you might be able to sublet a room from someone else who already has a lease. The original tenant remains legally responsible, but you still get a place to live.
  • Student housing: Some universities and colleges offer on-campus or university-affiliated apartments where the lease requirements are more flexible for students under 18.

It’s important to know that without a co-signer or special arrangement, most landlords won’t rent to minors, even if you have a steady income.

Renting at 18: More Than Just Age

Renting at 18: More Than Just Age

Reaching your 18th birthday means you’re legally allowed to sign a lease — but landlords look at more than just age before handing over the keys. They want to make sure you can reliably pay rent and take care of the property.

Here’s what most landlords will check:

1. Proof of Income

You’ll usually need to show you earn 2.5 to 3 times the monthly rent. Pay stubs, employment letters, or tax returns can serve as proof. If you’re a student, a co-signer’s income may be used instead.

2. Credit History

Landlords often run a credit check to see how you manage debt and payments. If you’re just starting out and don’t have much credit history, it’s not a dealbreaker — but a co-signer may still be required.
3. Rental or Personal References

References from previous landlords or employers help prove you’re responsible and reliable. If you’re renting for the first time, personal references (like a teacher or manager) can work too.

4. Security Deposit

Most landlords require a security deposit upfront, often equal to one month’s rent. Be prepared to pay this along with the first (and sometimes last) month’s rent before moving in.

Comparison: Renting Options by Age

Here’s a quick overview of how rental options and requirements typically change depending on your age:

Age Group Can You Sign a Lease? Co-Signer Needed? Common Options Special Notes
Under 18 No (in most cases) Yes Co-signed lease, student housing, sublet Must have an adult sign the lease.
18–20 Yes Sometimes Standard lease, co-signed lease Limited credit may require a co-signer.
21+ Yes Usually not Standard lease Full financial independence expected.

This table shows that turning 18 opens the door to renting, but financial stability and credit history still influence the process, especially in your late teens and early twenties.

Tips for Renting Your First Apartment at 18

Renting at 18 is absolutely possible — and many people do it every year. But because you’re just starting out financially, preparation goes a long way. Here are some tips to boost your chances of approval:

1. Build Your Credit Early

Consider getting a secured credit card or being added as an authorized user on a parent’s account before you apply. Even a few months of positive credit history can make a difference.

2. Save for Upfront Costs

Besides the security deposit, you’ll likely need to pay the first month’s rent (and sometimes the last). Budget for moving costs, furniture, and utilities too.

3. Get a Co-Signer (If Needed)

If your income or credit isn’t strong enough on its own, a co-signer with good credit can help you get approved. Just remember, they’ll be legally responsible if you miss payments.
4. Be Honest and Organized

Landlords appreciate clear communication. Have your documents ready — ID, proof of income, references — and be upfront if you’re new to renting. Responsibility counts for a lot.

What to Watch Out for as a First-Time Renter

What to Watch Out for as a First-Time Renter

It’s easy to get swept up in the excitement of renting your first apartment, but don’t rush into signing anything without understanding what you’re agreeing to. A few key points to double-check:

  • Lease terms: How long is the lease? What’s the notice period for moving out?
  • Additional fees: Are there charges for parking, pets, or maintenance?
  • Repairs and maintenance: Who is responsible for what?
  • Subletting rules: Can you have a roommate or sublet the apartment later?

If anything seems unclear, ask questions before signing. Once the lease is signed, you’re legally bound by its terms.
Renting as a Student: Special Considerations

If you’re 18 and heading to college, you might face slightly different rental scenarios:

  • Campus housing: Many schools offer dorms or on-campus apartments with more flexible eligibility rules.
  • Student apartments: Private complexes near campuses often cater to students, sometimes skipping credit checks or offering co-signer-friendly policies.
  • Roommates: Splitting rent with roommates can make renting more affordable and help you qualify if income requirements are high.

Student-focused housing often comes with perks like furnished units and shorter leases, but always read the fine print — the terms can vary widely.

FAQs About How Old You Have to Be to Rent an Apartment

1. Can you rent an apartment if you’re under 18?

Usually, no. Because minors can’t legally sign contracts, you’ll need a co-signer like a parent or guardian to rent before you turn 18. Alternatively, you might sublet a room or live in student housing with more flexible policies.

2. Do you need a co-signer at 18?

Not always, but many first-time renters do. If you don’t have a steady income, a strong credit history, or rental references, landlords may require a co-signer to reduce their risk.

3. Can a landlord refuse to rent to an 18-year-old?

A landlord can’t refuse you just because of your age if you’re legally an adult. However, they can deny your application for other reasons, such as insufficient income, poor credit, or lack of references.

4. How much money do I need to rent an apartment at 18?

It varies, but plan for at least three times the monthly rent in income and upfront costs like the security deposit, first month’s rent, and possibly the last month’s rent. Saving a few thousand dollars before applying is a smart move.

Stepping Into Independence: What to Expect

So, how old do you have to be to rent an apartment? In most places, the magic number is 18 — the age when you can legally sign a lease and take on the responsibilities of a tenant. But renting is about more than just age.

Landlords want to see that you’re financially stable, creditworthy, and ready to handle the obligations that come with your new home.

If you’re under 18, don’t lose hope — a co-signer or student housing can bridge the gap. And if you’re 18 and ready to rent, start preparing now: build your credit, save money, and gather your documents.

Renting your first apartment is a big step toward independence. With the right preparation, you can make that leap confidently — and enjoy the freedom that comes with having a place to call your own.

More From Author

if i sell my house for $300k how much do i get

If I Sell My House for $300K How Much Do I Get?

how big is 150 square feet

How Big Is 150 Square Feet? A Complete Guide

If I Sell My House for $300K How Much Do I Get?

When I sold my first home, I naively thought the $300,000 sale price meant $300,000 in my pocket. I was already planning what to do with the money—until I sat down at closing and saw how much came off the top. If you’re wondering “if I sell my house for $300k how much do I get,” the honest answer is: far less than $300,000.

Between paying off your remaining mortgage, covering agent commissions, closing costs, and other fees, the final number that lands in your bank account is usually tens of thousands of dollars lower. But understanding where every dollar goes can help you plan realistically—and avoid unpleasant surprises.

Why You Don’t Keep the Full $300,000

The sale price is the gross amount, not the net proceeds. Just like your paycheck isn’t the same as your take-home pay after taxes and deductions, your house sale will have money subtracted for various costs before you ever see it.

Here’s what usually reduces your proceeds:

  • Mortgage balance: Whatever you still owe your lender must be paid off first. 
  • Real estate commissions: Typically 5–6% of the sale price, split between your agent and the buyer’s agent. 
  • Closing costs: Around 1–3%, including title insurance, escrow fees, and transfer taxes. 
  • Repairs and staging: Costs to prepare the home for sale and make it appealing to buyers. 
  • Capital gains tax: Only applies if the home was not your primary residence or if your profit exceeds IRS exemption limits. 

Each of these pieces chips away at the total until the final net amount is what you actually receive.

Breaking Down the Numbers: A $300,000 Home Sale Example

Breaking Down the Numbers: A $300,000 Home Sale Example

Let’s run through a real-world example to see how much you might actually take home from a $300,000 sale.

Deduction Category Typical Cost Range Estimated Amount (on $300,000)
Outstanding Mortgage Varies by homeowner $150,000 (example balance)
Real Estate Commissions 5% – 6% $15,000 – $18,000
Closing Costs 1% – 3% $3,000 – $9,000
Repairs & Staging 0.5% – 2% $1,500 – $6,000
Capital Gains Tax (if any) Depends on profit & status Varies
Estimated Net Proceeds $120,000 – $130,000

This table assumes a remaining mortgage balance of about $150,000. If you owe more or less, your net proceeds will change accordingly.

And if the home is your primary residence and you meet IRS ownership and use requirements, you may not owe any capital gains tax on the profit.

Step-by-Step: How to Calculate Your Net Proceeds

Step-by-Step: How to Calculate Your Net Proceeds

Let’s break the process down into clear steps so you can estimate your take-home amount with confidence.

1. Find Out How Much You Still Owe

The largest deduction from your sale is typically the outstanding mortgage. Contact your lender to get the exact payoff amount, which may include a few days of accrued interest.

Example:
If you owe $150,000, that amount will be subtracted from your $300,000 sale price right away.

2. Subtract Real Estate Agent Commissions

Agent commissions are usually 5–6% of the sale price. On a $300,000 home:

  • At 5% = $15,000 
  • At 6% = $18,000 

These fees are split between your agent and the buyer’s agent and paid from the proceeds at closing.

3. Account for Closing Costs

Closing costs are another 1–3% of the sale price and cover services like:

  • Title insurance 
  • Escrow and settlement fees 
  • Transfer taxes 
  • Recording fees 
  • Attorney fees (if applicable) 

For a $300,000 sale, expect $3,000 – $9,000 in closing costs.

4. Factor in Repairs and Staging Costs

Before selling, many homeowners invest in minor repairs or staging to improve the property’s appeal. These costs vary widely depending on the home’s condition but can range from $1,500 to $6,000.

If the home is in great shape, you might spend little to nothing here. If significant repairs were needed, budget more.

5. Consider Capital Gains Tax (If Applicable)

If this was your primary residence and you’ve lived there for at least two of the past five years, you can typically exclude up to $250,000 of profit (or $500,000 for married couples filing jointly) from capital gains tax.

If it was an investment property, or your gain exceeds those limits, you may owe capital gains tax on the profit portion.

Estimating Your Take-Home Amount: A Sample Scenario

Let’s put all the steps together with a realistic example:

  • Sale price: $300,000 
  • Outstanding mortgage: $150,000 
  • Agent commissions (6%): $18,000 
  • Closing costs (2%): $6,000 
  • Repairs and staging: $3,000 

Calculation:

$300,000 (sale price)
− $150,000 (mortgage)
− $18,000 (commissions)
− $6,000 (closing costs)
− $3,000 (repairs/staging)
= $123,000 net proceeds

In this example, you’d walk away with around $123,000 after selling your $300,000 home. Of course, the number could be higher or lower based on your exact situation.

What If You Don’t Have a Mortgage?

What If You Don’t Have a Mortgage?

If your home is paid off, your net proceeds increase dramatically because you skip the largest deduction. Here’s what that might look like:

  • Sale price: $300,000 
  • Agent commissions (6%): $18,000 
  • Closing costs (2%): $6,000 
  • Repairs/staging: $3,000 

Net proceeds: $273,000

Still, even without a mortgage, selling costs can easily total $25,000+, so it’s important not to overlook them.


Hidden Costs That Can Surprise Sellers

Beyond the obvious deductions, a few other costs might reduce your final amount:

  • Prepayment penalties: Rare but possible if you pay off your mortgage early. 
  • Property taxes: You may owe prorated property taxes at closing. 
  • HOA fees: Some associations require sellers to pay transfer fees or dues. 
  • Buyer credits: If you agreed to cover part of the buyer’s closing costs, that amount comes out of your proceeds too. 

Review your closing documents carefully to make sure you understand every deduction before signing.

How to Maximize Your Net Proceeds

How to Maximize Your Net Proceeds

Here are some expert tips to keep more money in your pocket:

  • Negotiate the commission: Some agents may agree to a slightly lower rate, especially in a hot market. 
  • Shop around for services: Title companies and attorneys can vary in cost—get quotes to save on closing fees. 
  • Focus on cost-effective upgrades: Minor improvements like fresh paint or landscaping can boost your sale price without major expense. 
  • Sell during peak season: Homes often sell for more in spring and early summer, improving your bottom line. 

Small strategic moves can add thousands to your final check.

FAQs About Selling a $300,000 House

Q1: How much do I walk away with if I sell my house for $300,000?

On average, after paying off your mortgage, agent commissions, closing costs, and prep expenses, you might walk away with $120,000–$130,000. If you own the home outright, your net proceeds could exceed $270,000.

Q2: Can I avoid paying real estate commissions?

Yes, by selling “For Sale By Owner” (FSBO), but you’ll take on all the marketing, negotiation, and paperwork yourself. Buyers’ agents may still expect a commission, so plan accordingly.

Q3: Do I have to pay capital gains tax when I sell my home?

If it’s your primary residence and you’ve lived there for at least two of the last five years, you can exclude up to $250,000 (single) or $500,000 (married) of profit. Otherwise, you may owe capital gains tax on the gain.

Q4: What document shows my final net proceeds?

Your settlement statement (HUD-1 or Closing Disclosure) details every fee, deduction, and the final amount you’ll receive at closing. Always review this carefully before signing.

The Bottom Line: Plan Ahead for a Realistic Take-Home

If you’re asking, “if I sell my house for $300k how much do I get,” the answer is almost always less than you think.

Your mortgage balance, commissions, closing costs, and prep expenses all chip away at the total. In most cases, sellers net about 60–70% of the sale price after everything is deducted.

Planning ahead—knowing your payoff amount, estimating fees, and reviewing your settlement statement—can help you avoid surprises and make smarter financial decisions about what’s next.

And if your home sale is part of a bigger real estate journey, you might also want to explore how to buy a house without a realtor to save even more on future transactions.

More From Author

how big is 5 acres

How Big Is 5 Acres? A Complete Guide to Visualizing and Using This Land Size

how old do you have to be to rent an apartment

How Old Do You Have to Be to Rent an Apartment?

How Big Is 5 Acres? A Complete Guide to Visualizing and Using This Land Size

I still remember the first time someone told me they owned five acres of land. It sounded impressive — but I realized I had no real sense of what that actually meant. Was it massive? Manageable?

Could you build a neighborhood on it, or just a single house with a huge backyard? If you’ve ever asked yourself how big is 5 acres, you’re not alone.

The truth is, five acres is a substantial piece of property — 217,800 square feet to be exact — but its real-world size can be hard to imagine.

In this guide, I’ll break it down in practical, visual ways, show you how people use this much land, and answer some common questions you might have.

What Does 5 Acres Mean in Square Feet and Other Units?

Before we get into comparisons, let’s start with the basics. An acre is a unit of area commonly used in the United States to measure land.

  • 1 acre = 43,560 square feet
  • 5 acres = 217,800 square feet

If you prefer metric measurements, that’s about 20,234 square meters or roughly 2.023 hectares.

This number alone doesn’t mean much without context. So, let’s put it into perspective by comparing it to things we see and use every day.

How Big Is 5 Acres Compared to Familiar Spaces?

How Big Is 5 Acres Compared to Familiar Spaces?

When you hear “five acres,” it’s easy to picture a flat green field, but this much land can take many shapes — from a perfect square to a long, narrow rectangle. Regardless of the shape, the area stays the same.

Here’s how 5 acres stacks up against familiar places and objects:

Comparison Approximate Quantity in 5 Acres Notes
Football fields (with end zones) Just over 4 fields A standard field is about 1.32 acres
Median single-family homes Around 96 homes Based on 2,261 sq. ft. per home
Tennis courts About 77 courts Each is ~2,808 sq. ft.
King-size beds Over 5,000 beds Each is ~42 sq. ft.
New York City blocks Roughly 2 city blocks Size varies by block

This table shows why 5 acres is often considered a

Whether you’re comparing it to sports fields, homes, or even mattresses, it’s clear that this is plenty of room to work with.

What Are the Typical Dimensions of 5 Acres?

Because “5 acres” measures area and not shape, there’s no single set of dimensions. However, some common shapes help people plan layouts for building or farming.

Here are a few examples:

  • Perfect square: About 467 ft × 467 ft
  • Common rectangle: 330 ft × 660 ft
  • Long, narrow strip: ~41.25 ft wide and 1 mile long

The second option, 330 by 660 feet, is one of the most typical layouts you’ll find in rural or suburban areas. This size is often seen in small farms, homesteads, and residential subdivisions.

What Can You Do With 5 Acres of Land?

What Can You Do With 5 Acres of Land?

Now that we understand how big 5 acres is, let’s talk about what you could actually do with it. The possibilities are wider than most people realize.

1. Build a Spacious Home and Yard

If you’re dreaming of privacy and room to breathe, 5 acres is more than enough space for a large home with a pool, gardens, and outdoor amenities — while still leaving most of the property untouched. You could also divide the land into sections for a guest house, workshop, or detached garage.

2. Start a Homestead or Hobby Farm

For those interested in sustainable living, five acres is often considered the sweet spot. It’s enough land to grow fruits and vegetables, plant a small orchard, and raise animals like chickens, goats, or even a few cows. Many small homesteads operate comfortably on 5 acres or less.

3. Develop for Commercial Use

Five acres also opens doors to business opportunities. It’s enough room to build a retail complex, parking lot, or even a small theme park or RV campground. Developers often work with parcels this size for light industrial or mixed-use projects.

4. Subdivide and Sell Lots

Depending on local zoning laws, a five-acre plot could be subdivided into smaller lots and sold individually. For example, splitting it into half-acre or quarter-acre parcels could create a small residential development.

Visualizing 5 Acres: Real-World Examples

Still struggling to picture it? Here are some mental images that make how big is 5 acres easier to grasp:

  • Football fields: Imagine four full-sized football fields lined up next to each other — and then a little extra space. That’s roughly 5 acres.
  • Homes: Think about a suburban neighborhood with nearly 100 homes. That’s how many could fit on 5 acres if space were used efficiently.
  • City blocks: If you’ve ever walked two New York City blocks, you’ve covered a similar distance to the length of five acres.
  • Tennis courts: Picture 77 tennis courts side by side. That’s the scale of your land.

Why the Shape of Your Land Matters

While five acres always equals 217,800 square feet, the shape of the property can dramatically affect how you use it.

  • A square or near-square lot is ideal for building structures and maximizing usable space.
  • A rectangular plot might work better for farming rows of crops or setting up driveways and access roads.
  • A narrow, long strip may limit building options but can still be useful for trails, gardens, or linear projects like solar panel arrays.

Always check zoning regulations, easements, and setbacks before planning your project — these legal details can influence how much of those five acres you can actively use.

Things to Consider Before Buying 5 Acres

Things to Consider Before Buying 5 Acres

If you’re thinking about purchasing a five-acre property, here are a few key factors to keep in mind:

  • Location and zoning: Rules vary widely by region, so research what’s allowed before you buy.
  • Access to utilities: Rural lots might require extra investment in water, electricity, and internet connections.
  • Topography: Slopes, wetlands, and rocky soil can limit what you can build or plant.
  • Future goals: Consider whether you plan to expand, subdivide, or sell portions of the land down the line.

Understanding these factors ensures that your five acres will work for you long-term.

FAQs About How Big 5 Acres Really Is

1. How many houses can fit on 5 acres?

It depends on house size, layout, and local zoning laws. On average, you could fit around 96 median-sized homes (about 2,261 sq. ft. each) if space was used purely for housing.

2. How long does it take to walk across 5 acres?

If the land is square-shaped (~467 ft on each side), it would take about 1.5 to 2 minutes to walk across at a normal pace. Walking the perimeter (about 1,868 feet) would take around 6 to 8 minutes.

3. Can you farm on 5 acres?

Absolutely. Five acres is ideal for a small-scale farm or homestead. Many people grow produce, raise livestock, and even run profitable market gardens on this amount of land.

4. Is 5 acres considered a lot of land?

For residential purposes, yes — five acres is considered quite large. While it’s modest for large-scale commercial agriculture, it’s more than enough for a spacious home, hobby farm, or small business.

Wrapping It Up: Why 5 Acres Is Bigger Than You Think

When you break it down, how big is 5 acres isn’t just a math question — it’s an exploration of what’s possible. Five acres equals 217,800 square feet, which is more space than four football fields, enough for nearly 100 homes, or even room to start a small farm. Its potential depends on its shape, location, and how you plan to use it.

Whether you’re dreaming of a quiet homestead, planning a commercial venture, or simply trying to visualize just how much land you’re dealing with, five acres is a size that offers both flexibility and opportunity. It’s more than just a number — it’s space to build, grow, and imagine.

More From Author

how to find a lien on a property

How to Find a Lien on a Property Without Losing Your Mind (or Your Money)

if i sell my house for $300k how much do i get

If I Sell My House for $300K How Much Do I Get?

How to Find a Lien on a Property Without Losing Your Mind (or Your Money)

I’ll never forget the first time I tried to buy a house. I had saved for years, spent countless weekends touring open houses, and finally found a charming little fixer-upper that felt perfect. 

Then came the curveball: during the final steps, my real estate agent mentioned there might be an old contractor’s lien on the place. I froze. I had no idea what that meant or how to deal with it. 

That’s when I learned that knowing how to find a lien on a property isn’t just for lawyers — it’s something every buyer, seller, and even curious homeowner should understand.

If you’ve ever wondered how to uncover hidden debts or legal claims tied to a house, stick with me. I’ll share what I learned the hard way — from free DIY methods to expert-backed solutions — and make sure you never get blindsided like I did.

What Exactly Is a Lien and Why Should You Care?

What Exactly Is a Lien and Why Should You Care?

Before we talk about how to find a lien on a property, it’s worth understanding what a lien actually is. A lien is a legal claim against a property, usually because the owner owes someone money. It could come from unpaid property taxes, a contractor bill that was never settled, or even a court judgment.

The scary part? Liens stay with the property — not the person. So if you buy a house with an existing lien and don’t know about it, you could end up responsible for someone else’s debt. And trust me, that’s not a surprise you want after signing the biggest check of your life.

The good news is that liens are public record. That means you can find them — and with a bit of know-how, you can do it without hiring a lawyer.

Where Do You Start When Looking for Liens?

Where Do You Start When Looking for Liens?

When I first tried to figure out how to find a lien on a property, the process felt overwhelming. But once I broke it down, it was much simpler than I expected. The best starting point? Your local county offices.

The county recorder’s office (sometimes called the register of deeds or county clerk) is your go-to. This office keeps records of deeds, mortgages, and most liens filed against properties in that area. 

Many counties even have online search tools where you can look up liens using the property address or the owner’s legal name.

If online searches aren’t an option, you can visit the office in person. Staff can often help you search the records, and while viewing the documents might be free, you’ll likely pay a small fee if you want printed copies.

This step alone can reveal tax liens, contractor liens, and even some court-related claims. It’s a goldmine of information — and it’s available to anyone willing to do a little digging.

How Can You Search for Liens on Your Own?

I’ll be honest: the DIY route isn’t glamorous, but it’s empowering. Once you know how to find a lien on a property yourself, you’ll feel much more confident in any real estate deal.

Here’s how I do it step-by-step:

  1. Gather the basics. You’ll need the property’s address and the full legal name of the current owner.
  2. Start at the county recorder’s website. Many counties let you search public records for free or for a small fee. Look for anything labeled as a lien, claim, or encumbrance.
  3. Check the tax assessor’s office. This is where property tax records live. If taxes are unpaid, there may be a tax lien in place.
  4. Review court records. If the owner has any unpaid judgments against them, a creditor might have filed a judgment lien with the local courthouse.
  5. Check state and federal tax portals. Federal tax liens from the IRS are usually recorded locally, and many states have online portals where you can look up state tax liens.

The best part? Most of these searches are free or cost just a few dollars. If you’re willing to invest some time, you can uncover a lot without spending much money.

Should You Hire a Title Company Instead?

Should You Hire a Title Company Instead?

When I bought my second home, I decided not to go the DIY route. Instead, I hired a professional title company. If you’re serious about buying or selling, this is often the safest and most comprehensive option.

A title company specializes in uncovering every possible claim against a property. They don’t just check public databases — they dive deep into decades of records, ensuring nothing slips through the cracks. This is especially helpful for older homes, which may have a long and complicated ownership history.

There’s another bonus: title insurance. When you buy a home, the title company can issue insurance that protects you (and your lender) against financial losses if a hidden lien shows up later. It’s peace of mind that’s worth every penny.

Here’s a quick comparison of DIY vs. professional searches:

Method Cost Thoroughness Best For
DIY search Free – $20 Moderate Quick checks, curious homeowners
Title company $150 – $400 Very high Buyers, sellers, and real estate transactions

Why Is It So Important to Check for Liens?

Why Is It So Important to Check for Liens?

If you’re still wondering why all this matters, let me put it this way: skipping this step can cost you thousands. I once knew a buyer who skipped a proper lien search to “save time.” 

Weeks after closing, they received a letter about an unpaid contractor bill from three years earlier. It became their responsibility — even though they never hired that contractor.

When you understand how to find a lien on a property, you protect yourself from situations like that. It ensures:

  • Clear ownership: You know the seller legally owns the property.
  • No surprise debts: You won’t inherit someone else’s unpaid bills.
  • Financial security: Lenders feel more confident, which helps your loan process.

It’s a small effort now that can save you massive headaches later.

How Do You Handle a Lien If You Find One?

Finding a lien doesn’t always mean you should run away from the property. In many cases, liens can be resolved before closing. 

The seller might pay off the debt, negotiate with the creditor, or even challenge the lien in court if it’s invalid.

If you’re buying, make sure any lien is cleared before you close. Your real estate agent or title company can guide you through the process and ensure the property title is free and clear before your name goes on the deed.

FAQs About How to Find a Lien on a Property

Q1: Can I check for liens online for free?

Yes, many counties have free online search tools where you can look up liens by property address or owner name. If online access isn’t available, you can visit the recorder’s office in person.

Q2: Do liens show up on property listings?

Usually, they don’t. Property listings focus on selling points, not legal issues. That’s why it’s important to do your own search before buying.

Q3: How long does a lien stay on a property?

A lien typically stays until the debt is paid or the claim expires under state law. Some liens can last for years if they aren’t addressed.

Q4: Should I still buy a property with a lien?

It depends. If the lien will be cleared before closing, it’s usually fine. But if the seller refuses to resolve it, consider walking away or consulting a real estate attorney.

Wrap It Up: Don’t Let Liens Sneak Up on You

Learning how to find a lien on a property turned me from a nervous first-time buyer into someone who walks into real estate deals with confidence. Whether you choose the DIY route or bring in the pros, the key is not to skip this step.

Think of it as part of your due diligence — like checking under the hood before buying a car. It might not be the most exciting part of the process, but it’s one of the smartest. 

And once you’ve done it, you’ll know that the home you’re buying is truly yours — without anyone else’s debt attached. Your dream home deserves a clear title. Make sure you give it one.

More From Author

how long does an eviction stay on your record

How Long Does an Eviction Stay on Your Record? My Honest Guide to Bouncing Back

how big is 5 acres

How Big Is 5 Acres? A Complete Guide to Visualizing and Using This Land Size

How Long Does an Eviction Stay on Your Record? My Honest Guide to Bouncing Back

I’ll never forget the day I got that dreaded notice on my door. My stomach dropped, my palms went sweaty, and suddenly, every plan I had for the next year felt like it had been set on fire. 

If you’ve ever been through an eviction, you know the feeling — shame, panic, and about a thousand questions swirling in your head. The one that haunted me the most was, “How long does an eviction stay on your record?”

It’s a fair question because that single event can follow you around long after you’ve packed up and moved out. I had to learn the hard way that while some parts of an eviction fade with time, others stick like glue. 

But here’s the good news: understanding how it works — and what you can do about it — puts the power back in your hands.

What Actually Stays on Your Record After an Eviction?

What Actually Stays on Your Record After an Eviction?

When I first started trying to rent again, I assumed the eviction itself was haunting my credit score. I was wrong. The reality is a little more complicated — and a lot more manageable once you know the details.

There are two separate records to think about: your public record and your credit report. They’re not the same thing, and landlords may check either (or both) when you apply for a new place.

On your public record, the eviction lawsuit itself becomes a permanent entry. It doesn’t fall off after a few years or magically disappear. 

Court filings are public documents, and anyone — including potential landlords — can access them, often with just a quick search online. That means even an eviction from 10 years ago can technically still show up.

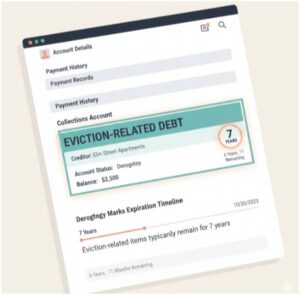
On your credit report, though, things work differently. The eviction itself won’t appear, but any related debt — like unpaid rent that went to collections or a civil judgment — will. 

That’s the part that usually stings your credit score. The silver lining? That negative mark typically drops off your credit report after seven years, just like most other debts.

How Long Does an Eviction Stay on Your Record With Landlords Checking?

How Long Does an Eviction Stay on Your Record With Landlords Checking?

Here’s where things get interesting. Even if your credit report is clean after seven years, the eviction lawsuit in your public record doesn’t have an expiration date. But whether it affects you depends on who’s looking and how they interpret it.

Big property management companies often have strict “no eviction” policies. They don’t care if it happened last year or last decade — they’ll deny your application outright. 

I ran into this a few times, and it was frustrating to know that a mistake from my past could still cost me a new home.

Smaller, independent landlords, however, tend to be more flexible. Many don’t even use automated tenant screening services and instead review applications personally. 

If you can explain your situation honestly and show that your circumstances have changed, they’re far more likely to give you a second chance. That human element matters more than most people realize.

Does Paying Off the Debt Help Remove the Eviction?

Does Paying Off the Debt Help Remove the Eviction?

One of the smartest things I did was address the unpaid rent tied to my eviction. It didn’t erase the public record, but it did help me rebuild trust with future landlords — and improve my credit.

If your eviction involved unpaid rent and that debt ended up as a judgment or collections account, paying it off can make a difference.

Once it’s marked “paid in full,” it looks a lot better to anyone reviewing your history. Some landlords may even be willing to help you get the judgment removed if you settle what you owe.

And here’s a bonus tip: after you pay off any outstanding debt, pull your credit report from one of the major agencies (Experian, Equifax, or TransUnion) to make sure it’s updated correctly. Sometimes errors slip through, and catching them early can save you headaches later.

How to Rent Again After an Eviction on Your Record

So, you’ve got an eviction in your past — now what? I’ve been there, and I promise it’s not the end of your renting life. With the right strategy, you can still land a great place.

Here’s what worked for me and for many others I’ve spoken to:

Be Honest and Tell Your Story

If a landlord asks about the eviction, don’t dodge it. I learned that trying to hide it only raised more red flags. Instead, I prepared a short, honest explanation: what happened, why it happened, and what’s changed since then. Most landlords appreciate honesty, and many are more forgiving when they understand the context.

Look for Private Landlords

Large apartment complexes often have rigid policies, but small “mom-and-pop” landlords make decisions on a case-by-case basis. They’re more likely to listen to your story and give you a chance if they see you’re stable and responsible now.

Offer Extra Security

Want to stand out as a trustworthy tenant? Offer a larger security deposit or pay a few months’ rent upfront. That gesture shows you’re serious and financially stable, which can outweigh concerns about your past.

Quick Comparison: Eviction on Public Record vs. Credit Report

Feature Public Record Credit Report
What Appears Eviction lawsuit filing Civil judgment or collections account for unpaid rent
Duration Permanent (does not expire) Typically removed after 7 years
Who Checks Landlords, tenant screening services Landlords, lenders, credit agencies
Can It Be Removed? No, but you can explain circumstances Yes, after 7 years or if paid and disputed
Impact on Renting Varies by landlord’s policy Affects credit score and financial trustworthiness

How Can You Check If the Eviction Is Still Showing?

Before you start apartment hunting again, do a little digging. I wish I had done this earlier — it would have saved me a lot of rejection and confusion.

First, search your name on your county or city court website to see if the eviction filing is still visible. Most jurisdictions have online databases now. If it’s there, it’s staying there — but you’ll know what potential landlords might see.

Next, request a copy of your credit report. Federal law lets you get one free report from each of the three major credit bureaus every year at AnnualCreditReport.com. Check for any unpaid rent accounts or judgments related to the eviction and see if they’ve aged off your report.

FAQs About How Long Does an Eviction Stay on Your Record

Does an eviction automatically fall off after seven years?

Not exactly. The debt from an eviction usually falls off your credit report after seven years, but the eviction lawsuit itself remains on public record indefinitely. That means landlords can still see it, even decades later, if they look in the right place.

Can you remove an eviction from your record?

You generally can’t erase a court filing from your public record. However, if you pay off any associated debt, you can sometimes work with the landlord to request that a judgment be removed. Even if it stays, resolving the debt improves your credibility with future landlords.

Will an eviction prevent me from renting again?

It depends on the landlord. Corporate property managers may deny your application, but many independent landlords are open to applicants with past evictions if they demonstrate financial stability and explain their situation honestly.

Does bankruptcy clear eviction records?

Filing for bankruptcy might discharge unpaid rent debt, but it doesn’t erase the eviction lawsuit from your public record. Landlords can still see that an eviction occurred, even if the financial part is resolved.

A Fresh Start Is Still Possible

I know firsthand how heavy an eviction can feel. It’s embarrassing, it’s stressful, and it can make you doubt your future. But it doesn’t define you — and it doesn’t mean you’ll never rent again.

The truth about how long does an eviction stay on your record is this: while the public record doesn’t disappear, the impact it has on your life can fade with time, responsibility, and transparency. Deal with any debt, own your story, and approach the rental process with honesty and confidence.

Your past might show up in a database, but it doesn’t have to hold you back from building a stable, comfortable home again. Trust me — I’ve been there, and you absolutely can bounce back.

More From Author

what is a penthouse

What Is a Penthouse? A Personal Take on Luxury Living Above the Clouds

how to find a lien on a property

How to Find a Lien on a Property Without Losing Your Mind (or Your Money)

What Is a Penthouse? A Personal Take on Luxury Living Above the Clouds

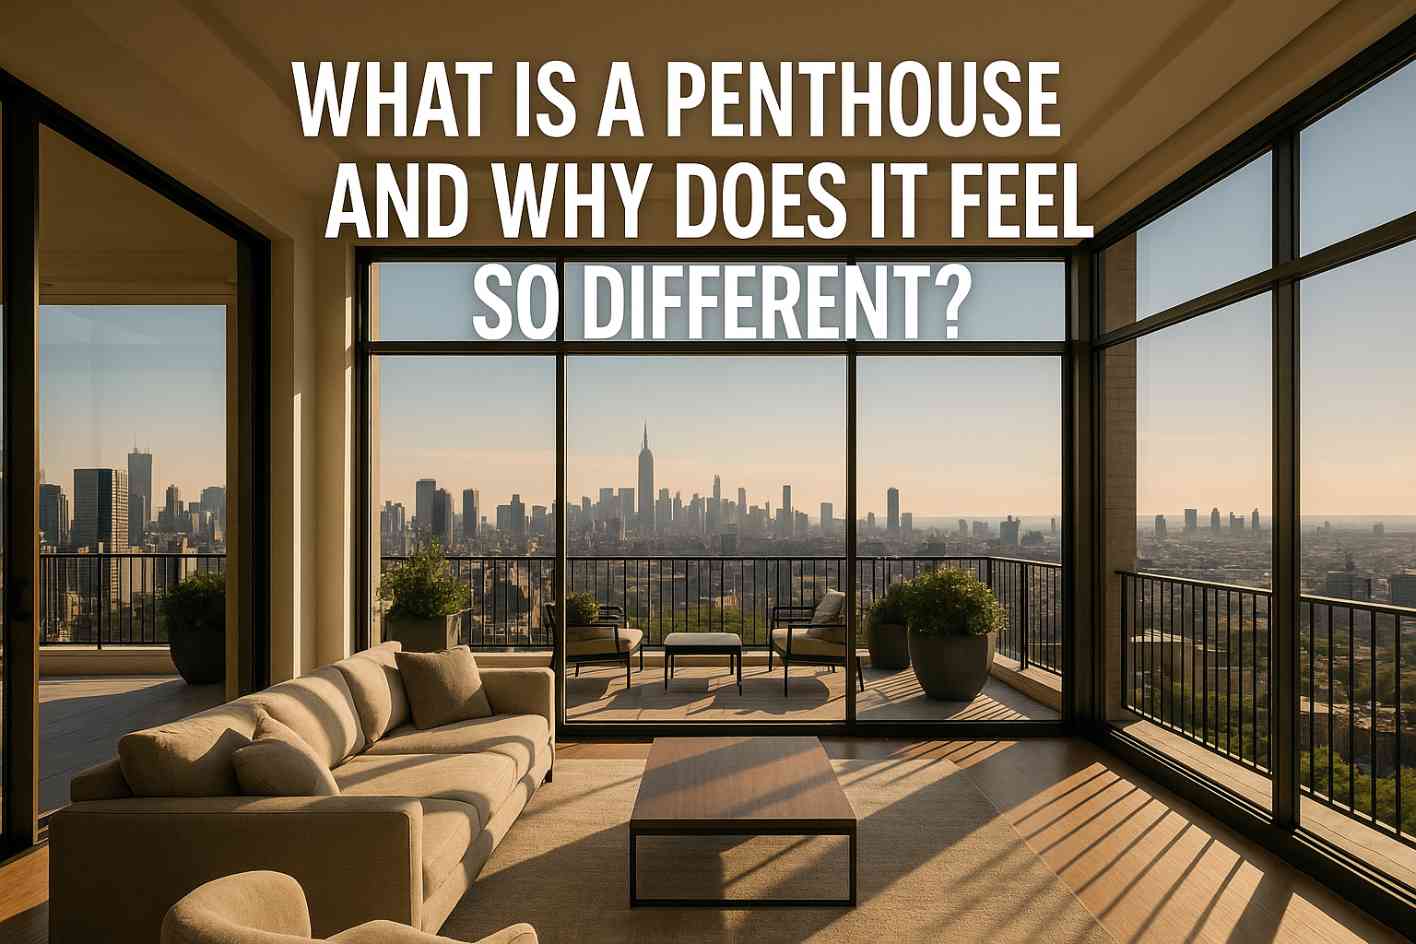
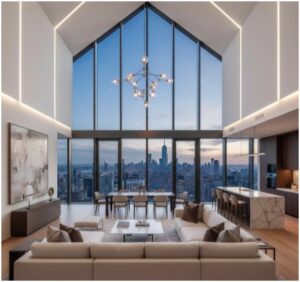
I’ll be honest with you — the first time I stepped into a penthouse, I didn’t know where to look. The skyline stretched endlessly before me, the ceilings soared higher than my imagination, and the terrace felt like a private park suspended in the sky. 

That was the day I truly understood what “living on top of the world” means. It also made me curious to dig deeper into what is a penthouse and why it’s considered the crown jewel of real estate.

If you’ve ever wondered why these sky-high homes are so coveted (and expensive), or whether they’re really worth the hype, you’re in the right place. 

I’ll break it down for you — no jargon, no fluff — just the real reasons why penthouses are the ultimate dream for anyone chasing comfort, status, and style.

What Is a Penthouse and Why Does It Feel So Different?

What Is a Penthouse and Why Does It Feel So Different?

At its core, what is a penthouse? It’s a luxury apartment perched on the highest floor of a high-rise building, offering more than just a place to live. It’s about space, privacy, and prestige. 

Unlike standard apartments, penthouses are designed to feel like independent homes in the sky. They’re bigger, brighter, and far more exclusive.

Historically, the top floors weren’t always desirable — they were harder to access and hotter in summer. But once elevators changed the game, the uppermost levels became the most sought-after spots. 

Today, developers sometimes even label multiple premium units as “penthouses” if they’re on the upper floors, even if they aren’t technically at the top. That’s how much power the word carries.

Living in a penthouse means waking up to panoramic views, hosting friends on a private terrace, and enjoying features most apartments can’t offer. It’s not just about square footage — it’s about lifestyle.

What Key Features Make a Penthouse So Special?

What Key Features Make a Penthouse So Special?

I remember thinking my first apartment was spacious… until I saw a penthouse. Everything felt supersized — from the ceilings to the windows to the open floor plan. 

But it’s not just about size. The magic of a penthouse lies in the combination of features that elevate it far above standard living.

1. Prime Location with Stunning Views

Being at the top means you’re surrounded by views most people only see in postcards. City skylines, riverbanks, mountain ranges — they’re all part of your everyday backdrop. And because you’re away from the hustle and bustle below, there’s a sense of peace and seclusion that’s hard to replicate.

2. Spacious and Customizable Layouts

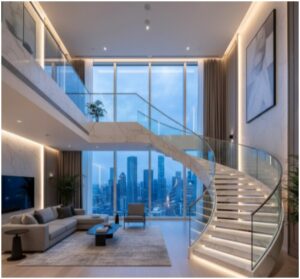
Penthouses often sprawl across one or two floors, sometimes connected by a private staircase. Fewer load-bearing walls mean you can shape the space to match your lifestyle — open-plan living, art galleries, home theaters, or whatever dream layout you imagine.

3. Private Outdoor Spaces

Terraces, balconies, and rooftop gardens aren’t just add-ons — they’re signature features. They offer the luxury of outdoor living in the middle of a city, perfect for morning coffee, weekend parties, or quiet sunsets.

4. Premium Amenities

Think designer kitchens, marble bathrooms, private elevators, maybe even a pool. Penthouses often come with exclusive access to building amenities like concierge services and fitness centers, turning daily life into something closer to a five-star hotel experience.

5. Enhanced Privacy

With fewer neighbors — sometimes none on the same floor — and often a separate entrance, you get unmatched privacy. It’s ideal if you value peace, security, and a little distance from the crowd.

What Types of Penthouses Can You Choose From?

What Types of Penthouses Can You Choose From?

Not all penthouses are created equal. Over the years, I’ve seen a surprising variety of them, each catering to different lifestyles and preferences. Here are the main types you’re likely to come across:

  • Duplex Penthouse: Spread over two levels, connected by an internal staircase, and often offering the feel of a luxury townhouse in the sky.
  • Modern Penthouse: Sleek, smart, and tech-savvy, with open floor plans, floor-to-ceiling windows, and minimalist design.
  • Hotel Suite Penthouse: Ultra-luxury suites in high-end hotels, often available for short-term stays and complete with butler services and VIP amenities.

Each type delivers a unique experience, but they all share one thing in common — they redefine what luxury living can be.

How Does a Penthouse Compare to a Regular Apartment?

How Does a Penthouse Compare to a Regular Apartment?

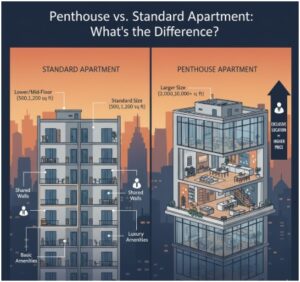
When people ask me about what is a penthouse, I often explain it best by comparing it directly to a standard apartment. Here’s how they stack up:

Feature Penthouse Apartment
Location Usually on the top floor Any floor
Space Much larger, sometimes multi-level Standardized layouts
Amenities Private elevators, designer features Shared, standard facilities
Privacy High, often exclusive floor Lower, shared corridors
Cost Premium pricing, higher maintenance More affordable

The difference is obvious — a penthouse isn’t just a bigger apartment. It’s a complete upgrade in lifestyle, privacy, and prestige.

What Should You Know Before Buying a Penthouse?

Now, here’s the part no one tells you during those glamorous property tours. While a penthouse is the pinnacle of luxury, it’s not all sunshine and champagne brunches. I learned this firsthand when I started researching the market myself.

Expect Higher Costs

The obvious one: penthouses come with a hefty price tag. Not just for the purchase itself but also for maintenance. Everything from cleaning those huge windows to servicing the private elevator adds to the cost.

Consider Weather Exposure

Being at the top means more direct exposure to heat, cold, and strong winds. Modern designs usually account for this, but it’s worth thinking about if you’re sensitive to temperature extremes.

Inventory Is Limited

There are usually only one or two penthouses per building. That scarcity makes them even more desirable — and often more expensive.

Plan for Elevator Dependence

If the elevator goes out of service, you’ll really feel it. Living several floors above the rest means you rely on that vertical ride more than you might realize.

Is a Penthouse Worth It for You?

Answering what is a penthouse is one thing, but deciding if it’s right for you is another. Ask yourself what you value most in a home. If privacy, panoramic views, and premium living are on your wishlist — and you’re ready for the costs that come with them — a penthouse can be an unmatched experience.

On the other hand, if you prioritize practicality, budget, or accessibility, a well-designed apartment might suit you just as well without the extra expense. The key is knowing your lifestyle and aligning your choices with it.

FAQs About Penthouses

Q1: Are penthouses always on the very top floor?

Not necessarily. Traditionally, yes, but modern developers sometimes brand multiple high-end units on upper floors as penthouses even if they’re not at the absolute top. The defining factor is exclusivity and premium features rather than just height.

Q2: Do penthouses have higher maintenance costs?

Yes, and significantly so. Larger spaces, luxury amenities, and private features like elevators or terraces require more upkeep. It’s essential to budget for those ongoing costs in addition to the purchase price.

Q3: Can I rent a penthouse instead of buying?

Absolutely. Many luxury buildings offer penthouses for rent, giving you a taste of sky-high living without the long-term commitment. Keep in mind, though, rental prices are usually steep.

Q4: Are penthouses a good investment?

They can be. Because of their exclusivity and limited supply, penthouses often retain strong resale value. However, their premium price point means the market is more niche, so they may take longer to sell than standard units.

Sky’s the Limit: My Final Word on Penthouses

So, what is a penthouse really? It’s more than a home — it’s a statement. It’s about waking up to sweeping views, enjoying your own private outdoor space above the city, and indulging in the best amenities modern living can offer. It’s the difference between living in a building and owning the crown jewel of it.

But here’s my honest take: the magic of a penthouse isn’t just in the marble floors or the panoramic windows — it’s in how it makes you feel. If your heart leaps a little higher at the thought of sipping coffee above the clouds, it might just be worth the climb.

More From Author

how much does it cost to move a mobile home

How Much Does It Cost to Move a Mobile Home? My Real-Life Breakdown of Every Dollar

how long does an eviction stay on your record

How Long Does an Eviction Stay on Your Record? My Honest Guide to Bouncing Back

How Much Does It Cost to Move a Mobile Home? My Real-Life Breakdown of Every Dollar

I’ll be honest with you—I never imagined I’d know this much about moving a mobile home. But a few years ago, when my aunt decided to relocate her cozy double-wide closer to family, I volunteered to help. I figured it’d be a simple task: hire a truck, hitch the home, and go. 

Oh, how wrong I was. By the time we wrapped up the move, I had a crash course in permits, escort vehicles, and setup costs. And the question I heard from everyone along the way was the same: how much does it cost to move a mobile home?

The truth is, there’s no one-size-fits-all number. It depends on size, distance, services, and a dozen other details. But after being deep in the trenches, I can walk you through the real-world costs—and help you plan your move without losing your mind or your budget.

What’s the Average Cost to Move a Mobile Home?

What’s the Average Cost to Move a Mobile Home?

Here’s the straightforward answer: moving a mobile home usually costs between $5,000 and $20,000, with most people paying around $9,000. That’s a wide range, but it makes sense once you realize how many variables are involved.

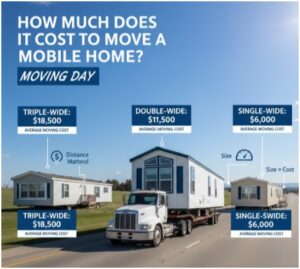
The home’s size is the biggest factor. A small single-wide is far cheaper to move than a sprawling triple-wide. Here’s a simple breakdown of typical local move costs (under 100 miles):

Mobile Home Size Typical Local Cost Range Average Local Cost
Single-Wide $4,000 – $8,000 $6,000
Double-Wide $8,000 – $15,000+ $11,500
Triple-Wide $12,000 – $25,000 $18,500

It’s worth noting that local moves cost less than long-distance hauls. Once you cross county or state lines, the price goes up—sometimes significantly.

How Does Distance Affect the Cost of Moving a Mobile Home?

How Does Distance Affect the Cost of Moving a Mobile Home?

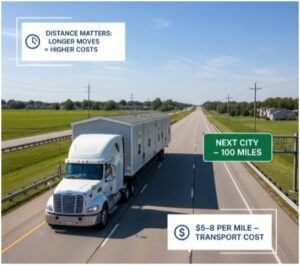
When I helped my aunt, we moved her home just 50 miles down the road. It wasn’t cheap, but it was manageable. If we’d gone a few hundred miles, the bill would have skyrocketed. Distance is one of the most important cost drivers.

For short moves (under 100 miles), you’re usually looking at $1,000 to $9,000 total. That might sound like a huge range, but the low end applies to smaller homes and transport-only services, while the higher end includes full-service moves and larger homes.

For long-distance relocations, moving companies often charge per mile, anywhere from $6 per mile for long hauls to $14 per mile for shorter hauls. 

And that’s just the transport cost. If your home is oversized, you might also need escort vehicles, which add $1.50 to $3.50 per mile.

So, if you’re dreaming of relocating your mobile home across state lines, remember that fuel, labor, and overnight stays all pile onto the bill. It’s not just about distance—it’s about everything distance adds.

What Services Are Included in the Cost to Move a Mobile Home?

What Services Are Included in the Cost to Move a Mobile Home?

Here’s something I didn’t realize until we started getting quotes: you’re not just paying to tow the house. You’re paying for a team to make the entire process safe, legal, and smooth.

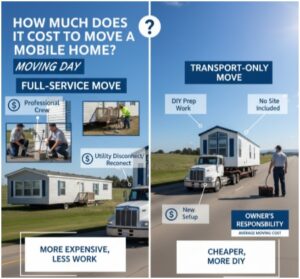
Most companies offer two types of service, and which one you choose dramatically affects how much you’ll pay:

Full-Service Move

This is the “we handle everything” option. It usually includes disconnecting utilities, securing appliances, transporting the home, getting permits, and setting everything back up at the new location. It’s convenient, stress-free, and pricey—adding several thousand dollars to your total cost.

Transport-Only Move

This budget-friendly option is what it sounds like: the movers transport the home, and you handle everything else. That means disconnecting utilities, prepping the home for transport, obtaining permits, and setting it up once it arrives. It’s cheaper but requires a lot more effort on your part.

If you’re like me and prefer peace of mind over DIY headaches, full-service is worth considering. But if you’re confident handling the prep work and want to save cash, transport-only can significantly cut costs.

What Other Factors Influence How Much It Costs to Move a Mobile Home?

After distance and service type, a few sneaky variables can shift your final price. When I was helping with my aunt’s move, I quickly learned that even the smallest details mattered. Here’s what else plays a role:

Age and Condition of the Home

Older mobile homes can be fragile and need extra work to make them safe for transport. That means more time, materials, and money. If your home hasn’t been moved in decades, expect to pay more.

Site Accessibility

The easier it is to access your current and new site, the less you’ll spend. Narrow roads, steep driveways, or tight corners add labor time and might require special equipment, increasing your bill.

Permits and Inspections

Crossing county or state lines? You’ll need permits from every jurisdiction along the way. Most moving companies handle this for you, but the fees add up. Wide-load moves often require escort vehicles, which cost extra too.

Season and Timing

Summer and the end of the month are peak moving times, so rates are often higher. If you have flexibility, consider moving during the off-season to save money.

How Can You Estimate Your Total Moving Cost?

Here’s my favorite part—doing a little math upfront can save you from sticker shock later. Think about it like this:

  1. Start with base cost: Use the average cost for your home size from the table above.
  2. Add distance charges: Multiply the mileage by the per-mile rate (typically $6–$14).
  3. Include permits and escorts: Estimate $1.50–$3.50 per mile for escort vehicles if needed.
  4. Factor in services: Full-service could add $2,000–$5,000 to your total.

With these rough numbers, you’ll have a ballpark idea before calling movers. But the most accurate way to know how much does it cost to move a mobile home is still to get quotes from licensed companies. 

They’ll assess your specific situation—distance, terrain, size, and condition—and give you a tailored estimate.

Why You Shouldn’t Try to Move a Mobile Home Yourself

I get it—DIYing a move sounds tempting when you see those numbers. But here’s the deal: moving a mobile home yourself is illegal in most states.

It’s not just about having the right truck or trailer. You need permits, inspections, and professional equipment to keep the home stable and secure. Without those, you risk damaging your home—or worse, facing fines and legal issues.

Hiring licensed movers isn’t just a recommendation; it’s a must.

FAQs About How Much It Costs to Move a Mobile Home

Q: Can I move a mobile home for less than $5,000?

A: Possibly, but only if it’s a small single-wide and the move is local. Even then, it depends on how much work you’re willing to do yourself. Most full-service moves cost more than $5,000, especially once you factor in permits and setup.

Q: Does moving a mobile home include reconnecting utilities?

A: Not always. Full-service moves usually include disconnecting and reconnecting utilities, but transport-only moves don’t. Make sure you clarify this with your moving company before signing a contract.

Q: How far can I move a mobile home?

A: Technically, as far as you want—some people move theirs across the country. But long-distance moves cost significantly more and require careful planning. Always budget for higher per-mile charges and additional permit requirements.

Q: Do I need special permits to move a mobile home?

A: Yes. Any move across county or state lines requires permits, and most wide-load moves need them too. Your moving company will usually handle this, but the fees are included in your final bill.

Final Thoughts: Moving Your Home Without Losing Your Cool

If you’ve been wondering how much does it cost to move a mobile home, now you know the truth—it’s not cheap, but it’s doable with smart planning. 

Whether you’re paying around $6,000 for a local single-wide move or $20,000 for a long-distance triple-wide relocation, the key is understanding what’s included and where you can save.

If I’ve learned anything from my aunt’s move, it’s this: preparation is everything. Get quotes, understand the services, and don’t skip the legal steps. Do that, and your home will roll into its new spot safe, sound, and ready for a fresh start.

More From Author

what does active under contract mean

What Does Active Under Contract Mean? My Real Estate Wake-Up Call Explained

what is a penthouse

What Is a Penthouse? A Personal Take on Luxury Living Above the Clouds

What Does Active Under Contract Mean? My Real Estate Wake-Up Call Explained

I’ll be honest: the first time I saw a house I loved marked “active under contract,” I thought I was too late. My heart sank faster than a dropped smartphone screen-first on concrete. 

But a few weeks later, that same house popped back on the market — and this time, my offer was accepted. 

That experience taught me a lesson that most buyers don’t learn until it’s almost too late: “active under contract” doesn’t mean the door is closed. It means the story isn’t over yet.

If you’ve ever fallen for a property only to see that confusing phrase attached to it, you’re not alone. 

Real estate jargon can feel like a secret language, but once you understand what it means — and how to play it smart — you’ll see opportunities most people overlook.

What Does Active Under Contract Mean in Real Estate?

What Does Active Under Contract Mean in Real Estate?

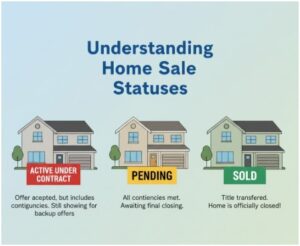
When a property is labeled “active under contract,” it means the seller has accepted an offer from a buyer — but the sale isn’t final. 

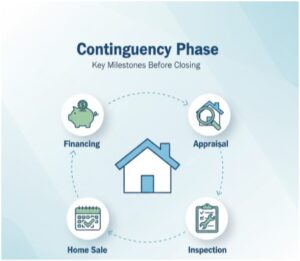
The deal is still in what’s called the contingency phase, a conditional period where several important boxes need to be checked before the sale can close.

Think of it as the “engaged” stage of a relationship. The house and buyer are committed, but they’re not married yet — and the wedding could still be called off. 

During this time, the property remains listed as active on the market. Sellers can keep showing it and even accept backup offers in case the first deal falls apart.

This phase typically lasts 30 to 60 days, and it’s where most real estate deals either move forward or unravel. 

Financing issues, inspection surprises, or low appraisals can all derail a sale — and that’s where opportunities for buyers like you come in.

Why Does a Property Stay Active Under Contract?

Why Does a Property Stay Active Under Contract?

I used to think “active under contract” was just a fancy way of saying “sold.” But now I know it’s about conditions — also known as contingencies — that protect both the buyer and seller. 

These contingencies have to be resolved within a specific timeframe before the deal can move forward.

Here’s a quick breakdown of the most common ones:

Contingency What It Means How It Affects the Deal
Financing The buyer needs final mortgage approval. If the loan is denied, the deal can collapse.
Appraisal The home must appraise at or above the sale price. A low appraisal could trigger price renegotiation or cancellation.
Inspection A professional inspects the home for issues. Major problems can lead the buyer to walk away if the seller won’t fix them.
Home Sale The buyer’s purchase depends on selling their current home. If their home doesn’t sell, they might back out.

If any of these conditions aren’t met, the contract can fall through — and the property goes back on the market. That’s why sellers keep the listing active. It’s their safety net.

What Does Active Under Contract Mean for Buyers Like Me (and You)?

What Does Active Under Contract Mean for Buyers Like Me (and You)?

Here’s the good news: you’re not out of the game. When I first learned this, it completely changed how I approached home hunting.

If you’re a buyer and a house you love is marked “active under contract,” you still have options — and understanding them can give you an edge.

First, you can still submit an offer. While the seller can’t accept it right away (because they’re already under contract), they can accept it as a backup. 

If the first deal fails, your offer might become the new primary one — without the property ever going back to public bidding.

Second, you can usually still tour the property. Many sellers continue showings during the contingency phase, especially if they’re open to backup offers. That’s your chance to fall in love with the place and be ready if the current deal collapses.

Here’s the reality check, though: your chances are lower because someone else has a head start. But they’re not zero. Deals fall apart more often than you’d think, and being second in line beats being nowhere in line at all.

What Does Active Under Contract Mean for Sellers?

From a seller’s perspective, keeping a property “active under contract” is a smart move — and one I’ll never underestimate again.

It offers a safety net. If the current buyer can’t secure financing, backs out after a bad inspection, or fails to sell their own home, the deal is off. 

By continuing to accept backup offers, the seller reduces the risk of starting from scratch if that happens.

It also gives them leverage. The knowledge that there are other interested buyers waiting in the wings can motivate the current buyer to meet contingencies quickly and avoid unnecessary delays.

In short, “active under contract” helps sellers stay in control during an unpredictable part of the selling process. It’s like keeping a Plan B ready while Plan A tries to work itself out.

How Is “Active Under Contract” Different From Other Real Estate Terms?

I used to lump “active under contract,” “pending,” and “contingent” together — but they’re not the same. Knowing the difference can help you read listings like a pro.

Status What It Means Backup Offers Accepted?
Active Under Contract Offer accepted, contingencies active, backup offers welcome. Yes
Pending All contingencies cleared, deal near finalization. No
Contingent Often used interchangeably with active under contract. Usually
Under Contract General term for an accepted offer. Sometimes

“Pending” is the stage where things are nearly wrapped up — the sale is about to close, and backup offers usually aren’t accepted. “Active under contract,” on the other hand, means the deal is far from done.

How Can You Take Advantage of an Active Under Contract Listing?

Here’s the strategy I wish I’d known sooner: treat “active under contract” as an invitation, not a rejection.

Start by talking to your agent. They can reach out to the seller’s agent and find out how far along the current deal is and whether backup offers are being considered. 

Sometimes, deals are on shaky ground, and your strong, prepared offer can look more attractive if the first buyer stumbles.

Next, get your financing pre-approved and have your paperwork ready. If the first contract falls apart, being ready to move fast can make all the difference in winning the property.

Finally, keep watching the listing. If it changes from “active under contract” to “pending,” your chances shrink dramatically. But if it suddenly goes back to “active,” it’s game on — and you’ll want to act quickly.

FAQs About What Does Active Under Contract Mean

Q1: Can I still make an offer on a house that’s active under contract?

Yes, you can. While the seller can’t accept it immediately, they can accept it as a backup. If the first deal falls through, your offer might automatically move into first position — sometimes without new negotiations.

Q2: How often do active under contract deals fall through?

It happens more often than you might think. Industry estimates suggest that about 5–10% of deals fail during the contingency phase. Financing and inspection issues are the most common reasons.

Q3: Should I schedule a showing for a home that’s active under contract?

If you’re serious about the property, yes. Many sellers still allow showings, especially if they’re open to backup offers. Seeing the property in person also helps you decide how aggressive you want to be with your backup offer.

Q4: What’s the difference between contingent and active under contract?

In many markets, they mean the same thing: the seller accepted an offer, but contingencies still need to be met. However, “active under contract” more clearly indicates that the seller is still open to backup offers.

The Final Word: Stay Ready, Stay Hopeful

Here’s the truth I learned the hard way: “active under contract” doesn’t mean the dream is dead — it just means the story isn’t finished. 

Whether you’re a hopeful buyer or a strategic seller, understanding what this status means helps you make smarter moves.

For buyers, it’s a reminder to stay prepared and keep an eye on opportunities others might ignore. For sellers, it’s a safety net that keeps options open until the deal is truly done.

And here’s my personal tip: real estate is a marathon, not a sprint. The house that slips away today might circle back tomorrow. I’ve lived it — and sometimes, being patient and persistent pays off in ways you never expected.

More From Author

housing for seniors based on income

Housing for Seniors Based on Income: My Guide to Finding a Place That Feels Like Home

how much does it cost to move a mobile home

How Much Does It Cost to Move a Mobile Home? My Real-Life Breakdown of Every Dollar

Housing for Seniors Based on Income: My Guide to Finding a Place That Feels Like Home

I’ll be honest — when my aunt turned 65 and decided she was done mowing lawns and fixing leaky faucets, we both thought finding affordable housing for seniors based on income would be as easy as typing a few words into Google. Spoiler: it wasn’t. 

We found ourselves tangled in acronyms like HUD and PHA, waiting lists that felt eternal, and forms longer than a CVS receipt. But here’s the thing — once we understood how these programs worked, everything changed. 

She’s now living in a cozy one-bedroom with neighbors her age, a shuttle that takes her to the grocery store, and rent she can actually afford.

If you’re helping a parent, relative, or even yourself navigate this maze, you’re in the right place. I’ve rounded up everything I wish someone had told me — and I promise to keep it practical, fun, and totally free of government-jargon headaches.

What Exactly Is Housing for Seniors Based on Income?

What Exactly Is Housing for Seniors Based on Income?

At its core, housing for seniors based on income is about making sure older adults — usually 62 and up — can live comfortably without draining their savings.

Instead of paying market rent, seniors pay a percentage of their income (often around 30%), and federal or local programs cover the rest.

The U.S. Department of Housing and Urban Development (HUD) runs most of these programs, but they’re managed locally through Public Housing Agencies (PHAs).

That means your experience in Chicago might look different from your cousin’s in Phoenix, but the goal is the same: safe, affordable housing that respects seniors’ budgets and independence.

How Does Section 202 Supportive Housing Work for Seniors?

How Does Section 202 Supportive Housing Work for Seniors?

If your idea of retirement includes less stress and more support, Section 202 might be the dream ticket. This program is specifically for very low-income seniors aged 62 and older. Nonprofits get federal funds to build or renovate housing, and seniors pay about 30% of their adjusted income for rent.

What makes Section 202 special is the extra help that often comes with it. Many communities offer services like meal programs, transportation, or housekeeping — all designed to help residents live independently longer. My aunt, for example, gets a free weekly ride to her doctor’s appointments, which is a game-changer.

How to apply: Unlike other programs, you don’t go through a central office. Instead, you apply directly to the management of the Section 202 property you’re interested in. HUD’s apartment locator is your best friend here — use it to find options near you.

Can I Use Section 8 Vouchers for Senior Housing?

Can I Use Section 8 Vouchers for Senior Housing?

Absolutely — and this option is perfect if you want flexibility. The Housing Choice Voucher Program (Section 8) doesn’t tie you to a specific building. Instead, it gives you a voucher you can use for privately owned housing that meets program requirements.

Here’s how it works: you pay 30% of your income toward rent, and your local PHA pays the rest directly to the landlord.

That means you could live in a small apartment downtown, a duplex near your grandkids, or a quiet complex in the suburbs — as long as the property qualifies.

Heads-up: Waitlists for Section 8 are notoriously long, and some PHAs prioritize elderly applicants. Apply to multiple agencies if possible. The sooner you’re on the list, the sooner your voucher can come through.

What About Public Housing for Seniors?

What About Public Housing for Seniors?

Public housing is the most straightforward form of housing for seniors based on income. It’s owned and managed by local PHAs and available to low-income families, people with disabilities, and seniors. Rent is, once again, about 30% of your adjusted income.

The main difference here is that public housing doesn’t usually come with the supportive services offered in Section 202 communities. It’s best suited for seniors who are independent and don’t need daily assistance. 

My neighbor’s mom, for example, loves her public housing apartment because it’s simple, central, and filled with people she’s known for years.

Who Qualifies for Income-Based Senior Housing?

Eligibility might vary slightly by program and location, but here’s the general breakdown:

Requirement What It Means
Age Most programs require you to be 62+, though some senior apartments accept residents 55+.
Income Your household income usually must be 50% or less of the Area Median Income (AMI). Some programs target 30% or less.
Citizenship You must be a U.S. citizen or have eligible immigration status.

Some programs may also consider disability status or veteran status, so it’s worth mentioning any relevant details when you apply.

How Do I Apply for Housing for Seniors Based on Income?

Here’s the part that feels like a treasure hunt — but I promise it’s doable if you take it step by step.

1. Contact Your Local Public Housing Agency (PHA)

Your PHA is your gateway to Section 8 vouchers and public housing options. You can find your local office using the directory on the HUD website. They’ll guide you through eligibility requirements, open waitlists, and application forms.

2. Search for Section 202 Properties

For supportive housing, you’ll need to contact property owners or managers directly. HUD’s apartment locator tool is the easiest way to find these properties. Remember, spots are limited, so apply to several communities if possible.

3. Use the Eldercare Locator

This free nationwide service (call 1-800-677-1116) connects seniors with local resources, including housing options. It’s a great way to get personalized help if you’re feeling overwhelmed by the process.

4. Talk to a HUD-Approved Housing Counselor

Housing counselors are trained to help you understand your options and complete your applications. They’re especially helpful if you’re applying for multiple programs or navigating complicated paperwork.

What Should I Expect After Applying?

I’ll be real with you — this is not a “submit today, move in tomorrow” situation. Housing for seniors based on income is in high demand, and waitlists can stretch for months or even years.

Some PHAs open their applications only once a year, sometimes for just a single day. That’s why it’s so important to apply early, apply often, and make sure every part of your application is complete. A single missing document can set you back months.

Patience is key here. My aunt waited almost a year for her Section 8 voucher, but she says it was worth every second. Once you’re approved, the peace of mind that comes with stable, affordable housing is unbeatable.

FAQs About Housing for Seniors Based on Income

1. Can someone under 62 qualify for income-based senior housing?

In most cases, no — programs like Section 202 and many senior apartments require at least one household member to be 62 or older.

However, some properties and age-restricted communities accept residents 55 and older, so it’s worth asking about specific age policies when applying.

2. How long are the waitlists for income-based senior housing?

Wait times vary wildly by location and program. In high-demand areas, waitlists for Section 8 vouchers can be several years.

Public housing waitlists might be shorter, but they still require patience. My tip? Apply to multiple programs and agencies to increase your chances of finding a spot sooner.

3. Are supportive services always included in senior housing?

Not always. Section 202 properties often include extras like transportation or meal assistance, but public housing typically does not.

Section 8 vouchers also don’t guarantee supportive services — you’re renting from a private landlord, so what’s included depends on the property.

4. Can I apply for more than one housing program at once?

Yes, and you absolutely should. There’s no rule against applying for Section 202, Section 8, and public housing simultaneously. Each has different wait times and requirements, and applying broadly gives you more options and better odds.

Wrapping It Up With a Roof Over Your Head

Here’s the truth: navigating housing for seniors based on income isn’t always easy. There’s paperwork, waiting, and a fair amount of patience required.

But once you get through it, the payoff is huge — stable rent, a safe community, and a home where you or your loved one can truly enjoy retirement.

If there’s one piece of advice I’d give, it’s this: start early. Even if you’re a few years away from needing it, getting on a waitlist now can save you headaches later.

And don’t be afraid to ask for help — from PHAs, housing counselors, or even a persistent niece who’s determined to crack the code (hi, that was me).

Affordable, comfortable senior living is possible — and now you know exactly where to start looking.

More From Author

Beachfront Properties: Dream Or Investment

Beachfront Properties: Dream Or Investment

what does active under contract mean

What Does Active Under Contract Mean? My Real Estate Wake-Up Call Explained