decoration tips decoradhouse from decoratoradvice, start writing letsbuildup.org blog, which diagram shows lines that must be parallel lines cut by a transversal?, best tech news feedcryptobuzz, dreamwithjeff com, start wizzydigital.org blog, about blog wizzydigital.org, why interior design is interesting mintpaldecor, how was teckaya construction equipment founded

A Complete Guide to Different Types of Fraud

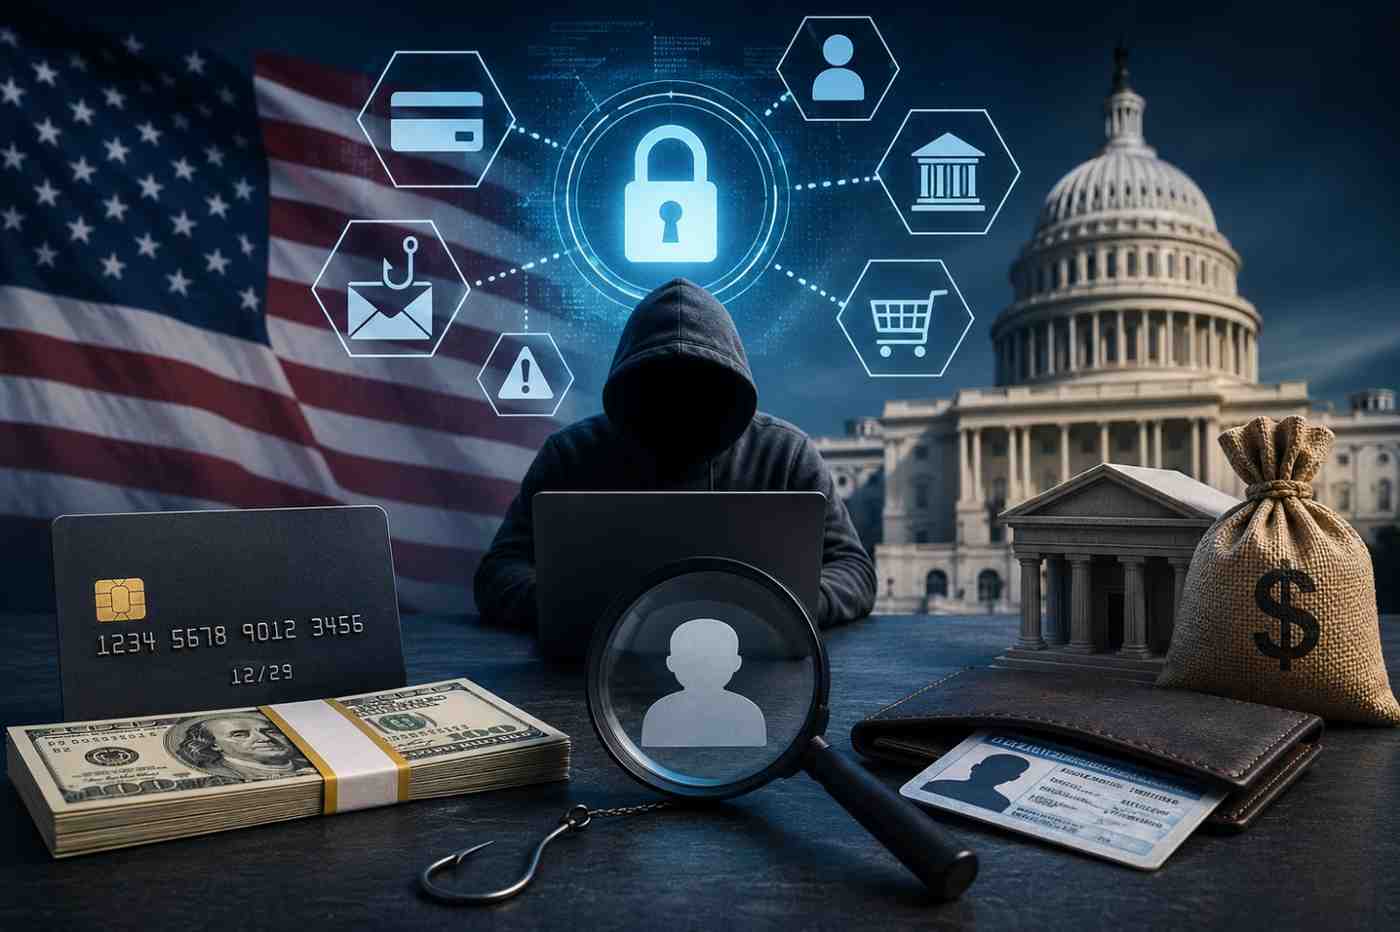
Fraud is a term frequently mentioned in legal circles and the media, yet many individuals find it difficult to fully grasp the breadth of what constitutes fraudulent activity. At its core, fraud is defined as the deliberate misrepresentation or concealment of information with the intent to deceive or manipulate someone into making decisions that benefit the perpetrator. This deception is carried out for personal or financial gain and can affect individuals, businesses, and government entities alike.

The Essential Components of Fraud
The Essential Components of Fraud

In legal terms, an act is generally classified as fraud if it meets four specific criteria:

  • Deceptive Intent: The perpetrator must intentionally misrepresent or falsify information.
  • Reliance: The victim must rely on this fraudulent information when taking an action or making a decision.
  • Harm: The victim must suffer some form of harm—financial, reputational, or otherwise—due to the act.
  • Financial Gain: The perpetrator seeks to benefit from the deception.

Common Types of Personal Fraud

Identity Theft

Identity theft is one of the most common and damaging forms of fraud. It occurs when a criminal steals personal information—such as Social Security numbers, bank account details, or credit card numbers—to impersonate a victim. Once obtained, this information is used to open fraudulent accounts, secure loans, or make unauthorized purchases in the victim’s name.

Financial and Investment Fraud

Financial fraud encompasses various schemes designed to illegally obtain money. Credit card fraud, involving the illegal use of another person’s card details for purchases, remains a global issue. Investment fraud includes more sophisticated operations like Ponzi schemes, where investors are lured by promises of high returns with little risk. Victims often discover too late that the investment opportunities were entirely fabricated.

Corporate and Occupational Fraud
Corporate and Occupational Fraud

Fraud within a business environment is an evolving challenge fueled by wrongful termination, technological, and economic shifts.

Financial Statement Fraud

This high-profile category involves intentionally altering or misrepresenting a company’s financial records. Motivations often include inflating profits to boost share prices or hiding losses to attract loans. A classic historical example is the Enron scandal, which resulted in billions of dollars in shareholder losses.

Asset Misappropriation

As the most frequent type of occupational fraud, asset misappropriation occurs when an employee steals or misuses organization resources for personal gain. This can take many forms, including skimming cash before it is recorded, falsifying expense reports, or creating “ghost” employees on the payroll.

Specialized Fraud Categories

Insurance and Healthcare Fraud

Insurance fraud occurs when an individual or organization misleads an insurance provider to receive undeserved benefits. Common examples include exaggerating damages after an accident, faking injuries, or staging automobile accidents. Similarly, healthcare fraud can involve billing for services never rendered or “upcoding” medical procedures to charge higher rates.

Tax Fraud

Tax fraud involves deliberate attempts to evade tax obligations by underreporting income, inflating expenses, or creating fictitious deductions. This crime is strictly monitored by authorities and can lead to severe penalties, including imprisonment.

Digital and Cyber Fraud
Digital and Cyber Fraud

The rise of technology has introduced new avenues for deception. Cyber fraud includes phishing, where fraudulent emails or websites are used to trick individuals into revealing sensitive data. Another growing threat is Business Email Compromise (BEC), where scammers impersonate executives to trick employees into wiring large sums of money.

Legal Consequences and Protection

Fraud is a serious criminal offense. Those found guilty can face harsh penalties, including significant fines, restitution to victims, and long-term imprisonment. Beyond criminal charges, perpetrators may be subject to civil lawsuits for damages. If you are facing allegations or have been targeted by such activities, consulting a criminal lawyer in St. George can help you navigate the complexities of the legal system and understand your rights.

To protect yourself, remain vigilant by monitoring your bank statements, using strong and unique passwords, and being skeptical of offers that seem “too good to be true”. Awareness and proactive steps are your best defense against the many faces of fraud.
More From Author

What to Know Before Moving to the United States

What to Know Before Moving to the United States

How to Organize Your Garage for Maximum Efficiency

How to Organize Your Garage for Maximum Efficiency

Wrongful Termination Explained: Know Your Rights Before It’s Too Late

 Losing a job can be stressful, but the situation becomes even more overwhelming when the termination feels unfair or unlawful. Wrongful termination occurs when an employer fires an employee in violation of legal rights, contractual agreements, or anti-discrimination laws. Understanding what qualifies as wrongful termination—and what steps you can take—can help you protect yourself and pursue justice if needed.

What Is Wrongful Termination?

Wrongful termination refers to a situation where an employee is dismissed for illegal reasons. While many workplaces operate under “at-will employment,” meaning employers can terminate employees at any time without cause, this does not grant them unlimited power. There are still clear legal boundaries that employers must respect.

Termination may be considered wrongful if it violates federal or state laws, breaches an employment contract, or infringes on protected rights. Knowing these boundaries is key to determining whether your dismissal was lawful or not.

Common Examples of Wrongful Termination

Common Examples of Wrongful Termination

Several scenarios may indicate wrongful termination. One of the most common involves discrimination. Employers cannot fire employees based on race, gender, age, religion, disability, or other protected characteristics. If your termination appears tied to any of these factors, it may be unlawful.

Another example is retaliation. If you were fired after reporting workplace misconduct, harassment, or illegal activities, your employer may have violated whistleblower protection laws. Employees have the right to speak up without fear of losing their jobs.

Breach of contract is also a potential basis for wrongful termination. If you have a written or implied contract outlining specific terms for dismissal and your employer fails to follow them, you may have a valid claim.

Finally, termination that violates public policy—such as firing someone for taking legally protected leave or serving on a jury—can also be considered wrongful.

Understanding Your Legal Rights

Employees are protected by a range of laws designed to ensure fair treatment in the workplace. These laws vary depending on your location, but they often include protections against discrimination, retaliation, and unfair labor practices.

If you believe you’ve been wrongfully terminated, it’s important to review your employment agreement, company policies, and any documentation related to your dismissal. These materials can provide valuable insight into whether your employer followed proper procedures.

Additionally, keep records of emails, performance reviews, and any incidents that may support your claim. Documentation plays a critical role in proving wrongful termination cases.

Steps to Take After a Suspected Wrongful Termination

Steps to Take After a Suspected Wrongful Termination

If you suspect your termination was unlawful, acting quickly can make a significant difference. Start by requesting a written explanation for your dismissal. This can help clarify your employer’s reasoning and may reveal inconsistencies.

Next, gather all relevant documents, including your employment contract, employee handbook, and communication records. These will be essential if you decide to pursue legal action.

It’s also wise to consult with a legal professional who specializes in employment law. An experienced business litigation attorney in Utah, for example, can evaluate your situation, explain your rights, and guide you through the process of filing a claim if necessary.

You may also need to file a complaint with the appropriate government agency before pursuing a lawsuit. Deadlines for filing claims can be strict, so it’s important not to delay.

The Impact of Wrongful Termination

Beyond financial loss, wrongful termination can take an emotional toll. Losing a job unexpectedly can affect your confidence, career trajectory, and personal well-being. That’s why understanding your rights is not just about legal protection—it’s also about regaining control over your situation.

Holding employers accountable for unlawful actions helps create safer and more equitable workplaces. It also ensures that others are not subjected to similar treatment.

Protecting Yourself Moving Forward

Protecting Yourself Moving Forward

Prevention is always better than reaction. Familiarize yourself with your company’s policies and your legal rights as an employee. Keep copies of important documents and maintain a record of any workplace issues.

If something feels off, trust your instincts and seek advice early. Being proactive can help you avoid potential disputes or strengthen your position if a conflict arises.

Final Thoughts

Wrongful termination is a serious issue that can have lasting consequences. While not every firing is illegal, understanding the difference can empower you to take action when necessary. By staying informed, documenting your experiences, and seeking professional guidance, you can protect your rights and move forward with confidence. Rejuvenate your mind and body through a proactive approach to managing your emotional and legal recovery.

If you ever find yourself questioning the legality of your dismissal, don’t ignore it. Acting early could make all the difference in securing the justice you deserve.

More From Author

5 Ways to Rejuvenate Your Mind and Body

5 Ways to Rejuvenate Your Mind and Body

6 Things to Know Before Filing for Retirement Benefits

6 Things to Know Before Filing for Retirement Benefits

Your Driver’s License: Easy to Lose, Hard to Get Back

Reaching for your keys is a reflex. Whether you are heading to work, picking up groceries, or rushing to a medical appointment, the ability to drive is often the glue holding a busy schedule together. We tend to view driving as a guaranteed right, but legally, it is a privilege—one that can be revoked faster than many realize.

The Fast Track to Suspension

Most drivers assume they are safe from suspension as long as they don’t commit a major crime. However, the threshold for losing your driving privileges is lower than you might think. A single lapse in judgment or a series of minor oversights can lead to a revocation.

Driving Under the Influence (DUI)

This is the most well-known reason for license suspension, and for good reason. All states have strict laws regarding driving under the influence of alcohol or drugs. In many jurisdictions, your license can be suspended immediately upon arrest, even before a court conviction. The length of the suspension varies significantly based on the severity of the offense and prior history, ranging from a few months to permanent revocation.

The Points System

You don’t need to commit a felony to lose your license; you might just need a heavy foot. Most states operate on a “points” system. Every time you are cited for a moving violation—like speeding, running a red light, or an improper lane change—points are added to your driving record.

If you accumulate a certain number of points within a specific timeframe (often 12 to 24 months), the state will automatically suspend your license. It’s a cumulative problem where small mistakes add up to a major penalty.

Non-Driving Violations

Surprisingly, your driving privileges can be revoked for actions that have nothing to do with operating a vehicle. State laws vary, but common non-driving reasons for suspension include:

Non-Driving Violations

  • Unpaid Fines: Ignoring a speeding ticket doesn’t make it go away. Failure to pay traffic citations often triggers an automatic suspension.
  • Unpaid Child Support: Many states use license suspension as a tool to enforce child support payments.
  • No Insurance: Driving without the state-minimum liability insurance is a quick way to get your license flagged and suspended.

The Uphill Battle of Reinstatement

Losing your license takes moments. Getting it back can take months or even years. The reinstatement process is rarely as simple as waiting out the suspension period. It involves a complex web of fees, paperwork, and legal requirements.

Financial Obligations

The cost of reinstatement goes beyond the original fine for your violation. You will typically have to pay a reinstatement fee to the Department of Motor Vehicles (DMV). If your suspension was due to unpaid tickets, you must settle those debts first. Court costs and legal fees can further inflate the price tag, making the process financially draining for many drivers.

Education and Evaluation

For alcohol-related suspensions or those resulting from reckless driving, the state often mandates remedial education. This might involve completing a defensive driving course or a substance abuse education program. In more severe cases, you may be required to undergo a professional drug and alcohol evaluation before you are even considered for reinstatement.

The SR-22 Insurance Requirement

One of the most persistent hurdles to reinstatement is the SR-22 form. This is a certificate of financial responsibility that verifies you have the required car insurance coverage.

If you are required to carry an SR-22, your insurance company must file it directly with the state. Because this flags you as a “high-risk” driver, your insurance premiums will likely skyrocket. You are generally required to maintain this status for several years; if you miss a payment or let the policy lapse, the insurance company notifies the state, and your license is suspended again immediately.

When You Have No Other Choice: Hardship Licenses

If your license is suspended, does that mean you can’t get to work to pay the fines you owe? It’s a vicious cycle. Recognizing this, many states offer a limited driving permit, often called a “hardship license,” “occupational license,” or “restricted license.”

These permits are not a “get out of jail free” card. They come with strict conditions. Typically, a hardship license allows you to drive only to specific locations, such as:

  • Work or school.
  • Medical appointments.
  • Court-ordered programs (like alcohol education classes).
  • Grocery stores or places of worship.

Obtaining one usually requires a hearing before a judge or a DMV officer. You must prove that the suspension is causing a significant hardship—for example, that no public transportation is available to get you to your job. If caught driving outside the permitted hours or locations, the hardship license is usually revoked, and the original suspension period is extended.

Protecting Your Right to Drive

The best strategy for dealing with license suspension is prevention. While some factors may seem out of your control, proactive behavior can keep your record clean.

Protecting Your Right to Drive

Monitor your driving record: Don’t let points sneak up on you. Check your driving record periodically to see where you stand. In some states, you can voluntarily take a defensive driving course to remove points from your record before they trigger a suspension.

Address citations immediately: If you receive a ticket, handle it right away. Pay the fine or schedule a court date. Letting it gather dust in your glove compartment is the fastest route to a suspended license.

Seek legal counsel for serious offenses: If you are charged with a major violation like a DUI or reckless driving, do not face the system alone. A qualified DUI attorney in Yakima, Washington, can help navigate the complex legal landscape. They may be able to negotiate reduced charges or alternative penalties that protect your driving privileges.

Review your insurance: Ensure your policy never lapses. Set up automatic payments so you don’t accidentally drive uninsured.

Conclusion

A driver’s license is your key to freedom—it allows you to work, care for your family, and live your life. Losing it can disrupt everything. The reinstatement process is intentionally difficult to deter negligence. By understanding the rules of the road and handling legal matters promptly, you can protect your license and keep your life on track.

More From Author

Essential Tips Every Psychologist Should Know

Essential Tips Every Psychologist Should Know for a Thriving Practice

How to Modernize Your Home Without Breaking the Bank

How to Modernize Your Home Without Breaking the Bank

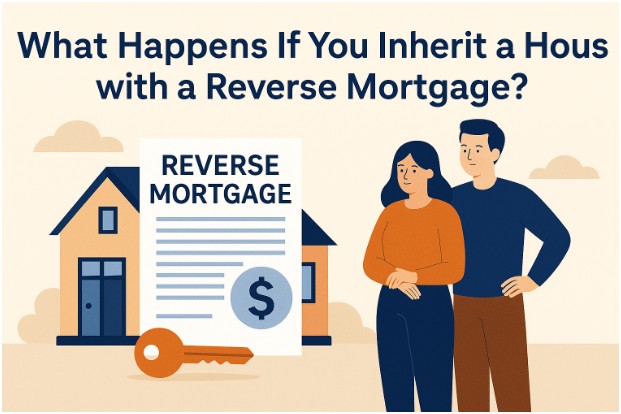
What Happens If You Inherit a House with a Reverse Mortgage? A Clear Guide for Heirs

If you inherit a house with a reverse mortgage, you face crucial decisions—and a deadline. Inheritance doesn’t erase the debt. Instead, the reverse mortgage becomes due and payable, and heirs must choose whether to keep, sell, or walk away. Below is a step-by-step guide to your options, timelines, and pitfalls, anchored in current HUD/CFPB rules.

Understanding the Reverse Mortgage After Death

Understanding the Reverse Mortgage After Death

How a Reverse Mortgage Matures (or “becomes due”)

A reverse mortgage matures when the last borrower (or eligible non-borrowing spouse) dies, permanently moves out, or fails to maintain residency. Once this maturity event occurs, the loan becomes due and payable.

At that point, heirs are on the clock. The servicer typically issues a Due & Payable notice and gives heirs an opportunity to respond.

Non-Recourse Protection & the 95% Rule

Reverse mortgages (especially HECMs) include a non-recourse feature: heirs or estates can’t be held responsible beyond the home’s value. 

If the loan balance exceeds the home’s appraised value, heirs typically may pay 95% of the appraised value (rather than the full balance) to keep the property. 

That “95% rule” ensures that heirs aren’t forced to cover a shortfall beyond what the home is worth. 

Your Options as an Heir

Your Options as an Heir

Option 1: Keep the Home (Pay Off or Refinance)

If you want to keep the inherited home, you must pay off the reverse mortgage. That payoff is either:

  • The full outstanding balance, or
  • 95% of the current appraised value, whichever is less.

If you don’t have cash, you might refinance the reverse mortgage into a traditional forward mortgage.

Option 2: Sell the Home

You or the estate can sell the home, using the sale proceeds to pay off the reverse mortgage. Any surplus goes to the heirs. 

If the home’s sale price doesn’t cover the mortgage, the non-recourse protection ensures heirs aren’t on the hook for the shortfall.

Option 3: Surrender / Walk Away

If maintaining or refinancing isn’t feasible, heirs can simply surrender the home (i.e. do nothing). The lender must foreclose through standard procedures—estate or heirs owe nothing beyond the home. 

Even if heirs are on the title, they can walk away at no cost under the non-recourse terms.

Critical Timeline: Respond Quickly

Heirs don’t have unlimited time. Here’s the usual timeline:

Stage Deadline / Timeframe Action Required
Due & Payable Notice ~30 days after maturity event Heirs must respond whether they intend to keep, sell, or surrender.
Settlement Period ~6 months Heirs must settle (pay off or sell). 
Extensions Two 90-day extensions possible (up to ~12 months total) Extensions often granted in writing if requested early.

If no response or action is taken, foreclosure may proceed.

It’s vital to communicate with the servicer early and request extension in writing so you don’t lose your options.

Special Case: Spouse Situations

Co-Borrowing Spouse

If your spouse was a co-borrower, they often retain the right to stay and continue payments under many reverse mortgage rules. 

Eligible Non-Borrowing Spouse

A spouse who was not a co-borrower but qualifies under HUD’s rules (e.g. was married at origination, remained married, and lived in the home) may continue residing in the home.

Ineligible Spouses or Other Heirs

If you’re an ineligible spouse or a non-spousal heir, you must choose among the three options above (pay off, sell, or walk away). 

Practical Steps for Heirs

Practical Steps for Heirs

  • Obtain the most recent mortgage statement — Know the loan balance, servicing details, and insurer.
  • Request an appraisal — To understand whether the home’s value is above or below the mortgage.
  • Communicate your intentions to the servicer — Inform them if you intend to keep, sell, or surrender the property.
  • Use extensions if needed — Apply in writing before the initial period expires.
  • Transfer title (via probate or trust) — The servicer won’t deal with you until you prove legal ownership.
  • Choose your path — Refinance, sell, or hand off the property. Don’t delay.

Frequently Asked Questions (Before Conclusion)

  • How long do heirs have to respond when they inherit a house with a reverse mortgage?

Heirs typically have about 30 days from notice to respond to the lender with their intention (sell, keep, or surrender).

  • What is the 95% rule in a reverse mortgage inheritance scenario?

If the reverse mortgage balance is more than the home’s appraised value, heirs may pay 95% of the appraised value (rather than the full balance) to retain the home. 

  • Can I refinance the reverse mortgage after inheriting the home?

Yes — if you become the legal titleholder, you may refinance to a traditional mortgage and pay off the reverse mortgage.

  • What happens if heirs do nothing after inheriting a house with a reverse mortgage?

If heirs take no action, the lender may foreclose through legal proceedings. Heirs owe nothing beyond the property value, thanks to non-recourse protections. 

The Takeaway: Don’t Delay Your Decision

Inheriting a house with a reverse mortgage means the clock starts ticking. The loan becomes due, and you need to decide whether to keep the property by paying it off (often at 95% of its appraised value), sell it and pocket the equity, or simply walk away without owing anything more. Acting quickly and communicating with the loan servicer is key to preserving all your options.

If you do decide to keep the property, this experience can even help you understand how to buy a house without a realtor — because handling the payoff, refinancing, and paperwork yourself teaches you a lot about the home-buying process.

The most important thing is to move forward with a clear plan and not let deadlines slip by. With the right knowledge and timely action, inheriting a home with a reverse mortgage doesn’t have to feel overwhelming — it can become an opportunity.

More From Author

how much is a double wide trailer

How Much Is a Double Wide Trailer? A Real-World 2025 Buyer’s Guide

questions to ask when touring an apartment

Questions to Ask When Touring an Apartment: A Renter’s Field Guide

How Old Do You Have to Be to Rent an Apartment?

Finding your first place to live is exciting — a milestone of independence that often marks the transition into adulthood.

But before you start scrolling through listings and picturing how you’ll decorate your new space, there’s one practical question you need answered: how old do you have to be to rent an apartment?

The short answer is simple: in most places, you must be at least 18 years old to legally rent an apartment. That’s because a lease is a binding legal contract, and minors generally can’t enter such agreements on their own.

But the full story involves more than just age — things like income, credit history, and co-signers often play just as big a role.

Why Age Matters When Renting an Apartment

The age requirement to rent isn’t set by landlords — it’s based on contract law. In most countries, and across all U.S. states, 18 is the legal age of adulthood. That means you can sign contracts, make financial commitments, and be held legally responsible for the terms you agree to.

A lease is exactly that: a legal agreement between you (the tenant) and the property owner (the landlord). It spells out your rights and responsibilities, from how much rent you’ll pay and when, to how the property must be maintained.

Because minors typically can’t be held legally responsible for contracts they sign, landlords require tenants to be 18 or older.

What Happens If You’re Under 18?

What Happens If You’re Under 18?

If you’re younger than 18 and eager to move out — maybe for college, work, or personal reasons — don’t worry. Renting isn’t off the table entirely. You’ll just need someone legally able to sign the lease with you.

Here’s how that usually works:

  • Guarantor or co-signer: A parent, guardian, or another trusted adult can sign the lease alongside you. They’ll be legally responsible for the rent and any damages if you fail to meet your obligations.
  • Subletting: In some cases, you might be able to sublet a room from someone else who already has a lease. The original tenant remains legally responsible, but you still get a place to live.
  • Student housing: Some universities and colleges offer on-campus or university-affiliated apartments where the lease requirements are more flexible for students under 18.

It’s important to know that without a co-signer or special arrangement, most landlords won’t rent to minors, even if you have a steady income.

Renting at 18: More Than Just Age

Renting at 18: More Than Just Age

Reaching your 18th birthday means you’re legally allowed to sign a lease — but landlords look at more than just age before handing over the keys. They want to make sure you can reliably pay rent and take care of the property.

Here’s what most landlords will check:

1. Proof of Income

You’ll usually need to show you earn 2.5 to 3 times the monthly rent. Pay stubs, employment letters, or tax returns can serve as proof. If you’re a student, a co-signer’s income may be used instead.

2. Credit History

Landlords often run a credit check to see how you manage debt and payments. If you’re just starting out and don’t have much credit history, it’s not a dealbreaker — but a co-signer may still be required.

3. Rental or Personal References

References from previous landlords or employers help prove you’re responsible and reliable. If you’re renting for the first time, personal references (like a teacher or manager) can work too.

4. Security Deposit

Most landlords require a security deposit upfront, often equal to one month’s rent. Be prepared to pay this along with the first (and sometimes last) month’s rent before moving in.

Comparison: Renting Options by Age

Here’s a quick overview of how rental options and requirements typically change depending on your age:

Age Group Can You Sign a Lease? Co-Signer Needed? Common Options Special Notes
Under 18 No (in most cases) Yes Co-signed lease, student housing, sublet Must have an adult sign the lease.
18–20 Yes Sometimes Standard lease, co-signed lease Limited credit may require a co-signer.
21+ Yes Usually not Standard lease Full financial independence expected.

This table shows that turning 18 opens the door to renting, but financial stability and credit history still influence the process, especially in your late teens and early twenties.

Tips for Renting Your First Apartment at 18

Renting at 18 is absolutely possible — and many people do it every year. But because you’re just starting out financially, preparation goes a long way. Here are some tips to boost your chances of approval:

1. Build Your Credit Early

Consider getting a secured credit card or being added as an authorized user on a parent’s account before you apply. Even a few months of positive credit history can make a difference.

2. Save for Upfront Costs

Besides the security deposit, you’ll likely need to pay the first month’s rent (and sometimes the last). Budget for moving costs, furniture, and utilities too.

3. Get a Co-Signer (If Needed)

If your income or credit isn’t strong enough on its own, a co-signer with good credit can help you get approved. Just remember, they’ll be legally responsible if you miss payments.

4. Be Honest and Organized

Landlords appreciate clear communication. Have your documents ready — ID, proof of income, references — and be upfront if you’re new to renting. Responsibility counts for a lot.

What to Watch Out for as a First-Time Renter

What to Watch Out for as a First-Time Renter

It’s easy to get swept up in the excitement of renting your first apartment, but don’t rush into signing anything without understanding what you’re agreeing to. A few key points to double-check:

  • Lease terms: How long is the lease? What’s the notice period for moving out?
  • Additional fees: Are there charges for parking, pets, or maintenance?
  • Repairs and maintenance: Who is responsible for what?
  • Subletting rules: Can you have a roommate or sublet the apartment later?

If anything seems unclear, ask questions before signing. Once the lease is signed, you’re legally bound by its terms.

Renting as a Student: Special Considerations

If you’re 18 and heading to college, you might face slightly different rental scenarios:

  • Campus housing: Many schools offer dorms or on-campus apartments with more flexible eligibility rules.
  • Student apartments: Private complexes near campuses often cater to students, sometimes skipping credit checks or offering co-signer-friendly policies.
  • Roommates: Splitting rent with roommates can make renting more affordable and help you qualify if income requirements are high.

Student-focused housing often comes with perks like furnished units and shorter leases, but always read the fine print — the terms can vary widely.

FAQs About How Old You Have to Be to Rent an Apartment

1. Can you rent an apartment if you’re under 18?

Usually, no. Because minors can’t legally sign contracts, you’ll need a co-signer like a parent or guardian to rent before you turn 18. Alternatively, you might sublet a room or live in student housing with more flexible policies.

2. Do you need a co-signer at 18?

Not always, but many first-time renters do. If you don’t have a steady income, a strong credit history, or rental references, landlords may require a co-signer to reduce their risk.

3. Can a landlord refuse to rent to an 18-year-old?

A landlord can’t refuse you just because of your age if you’re legally an adult. However, they can deny your application for other reasons, such as insufficient income, poor credit, or lack of references.

4. How much money do I need to rent an apartment at 18?

It varies, but plan for at least three times the monthly rent in income and upfront costs like the security deposit, first month’s rent, and possibly the last month’s rent. Saving a few thousand dollars before applying is a smart move.

Stepping Into Independence: What to Expect

So, how old do you have to be to rent an apartment? In most places, the magic number is 18 — the age when you can legally sign a lease and take on the responsibilities of a tenant. But renting is about more than just age.

Landlords want to see that you’re financially stable, creditworthy, and ready to handle the obligations that come with your new home.

If you’re under 18, don’t lose hope — a co-signer or student housing can bridge the gap. And if you’re 18 and ready to rent, start preparing now: build your credit, save money, and gather your documents.

Renting your first apartment is a big step toward independence. With the right preparation, you can make that leap confidently — and enjoy the freedom that comes with having a place to call your own.

More From Author

if i sell my house for $300k how much do i get

If I Sell My House for $300K How Much Do I Get?

how big is 150 square feet

How Big Is 150 Square Feet? A Complete Guide