decoration tips decoradhouse from decoratoradvice, start writing letsbuildup.org blog, which diagram shows lines that must be parallel lines cut by a transversal?, best tech news feedcryptobuzz, dreamwithjeff com, start wizzydigital.org blog, about blog wizzydigital.org, why interior design is interesting mintpaldecor, how was teckaya construction equipment founded

Future-Proof Your Finances: Retirement Planning Tips That Work

For many hardworking entrepreneurs, their business is more than just a source of income—it is a passion, a lifestyle, and a legacy. However, this deep immersion in day-to-day operations often leads to one critical oversight: comprehensive retirement planning.

Unlike traditional employees who benefit from structured corporate matching, business owners must take active, deliberate steps to build their own safety nets.

Future-proofing your finances requires a strategic approach that aligns your personal retirement goals with your company’s lifecycle. Whether you are decades away from stepping down or starting to see the finish line, here are practical, actionable retirement planning tips that work.

1. Define Your Post-Business Vision Early

You cannot plan a journey without a clear destination. Successful retirement planning begins by answering essential questions about what you want your future to look like.

Do you plan to fully step away from daily operations, or would you prefer to retain a partial ownership stake and act as an advisor? Will you need a major lump-sum payout to fund your lifestyle, or are you looking to generate ongoing passive income?

Defining these goals early—ideally three to ten years before your target retirement date—gives you a definitive roadmap. It allows you to calculate your actual financial needs based on your projected expenses, lifestyle choices, and inflation.

A practical budget can make those future goals easier to measure. Following the 50/30/20 rule can help you divide income among essential expenses, lifestyle spending, and savings or debt repayment, creating a consistent structure for increasing retirement contributions over time.

2. Maximize Entrepreneur-Specific Savings Accounts
Maximize Entrepreneur-Specific Savings Accounts

Many business owners make the mistake of reinvesting 100% of their profits back into their company. While growth is essential, diversifying your savings is vital. Fortunately, the tax code offers several robust retirement savings vehicles designed specifically for self-employed individuals and small business owners:

  • Solo 401(k):Perfect for sole proprietors, this plan allows you to make contributions as both an employee and an employer, maximizing your tax-deferred savings.
  • SEP IRA: A Simplified Employee Pension plan lets you contribute a percentage of your net earnings, offering high contribution limits and flexible annual funding.
  • SIMPLE IRA: Ideal for businesses with a small team, this plan allows employee contributions while requiring matching contributions from your business.

Utilizing these accounts not only builds a dedicated retirement nest egg but also provides immediate tax advantages that reduce your current taxable income.

3. Diversify Beyond Your Business Assets

Your business may currently be your most valuable asset, but relying on it as your sole retirement vehicle is a high-risk strategy. Market shifts, economic downturns, and unexpected industry disruptions can instantly impact your company’s valuation.

Personal debt decisions can also affect how much money remains available for retirement contributions and long-term investments. For example, understanding fixed vs variable auto loans can help you choose between predictable monthly payments and rates that may change over time, allowing you to protect your cash flow while working toward your retirement goals.

To secure your financial future, build a diversified investment portfolio. Allocate assets across stocks, bonds, mutual funds, and real estate. This deliberate separation of personal wealth from business performance ensures that even if your industry faces headwinds, your retirement security remains entirely intact.

4. Treat Your Business as a Retirement Asset
Treat Your Business as a Retirement Asset

For most entrepreneurs, the ultimate liquidity event is the transition of their company. However, extracting maximum value from your business requires meticulous preparation.

To prepare your business for the market, you must focus on clean bookkeeping, operational independence, and strong financial performance.

When the time comes to sell a business in Salt Lake City, buyers will look for a turnkey operation that can run seamlessly without its founder.

By documenting standard operating procedures, strengthening customer relationships, and resolving outstanding liabilities now, you can significantly increase your company’s market value and secure a larger payout for your retirement.

5. Craft a Robust Succession Plan

If you plan to keep the business running after you retire—perhaps by passing it to family members or key employees—you need a formal succession plan. A successful transition is rarely immediate; it requires a structured timeline to transfer knowledge, hand over daily responsibilities, and train your successor.

A clear succession plan protects the continuity of the business, maintains employee morale, and ensures that the transition does not disrupt the company’s financial stability, which may still be funding your retirement through equity or installment payments.

Take the Next Step

Future-proofing your finances is not a single, one-time event; it is an ongoing process of adjustment and optimization. By combining dedicated retirement accounts, personal asset diversification, and professional exit planning, you can transition into your next chapter with complete financial confidence.

Don’t leave your legacy to chance. Reach out to a trusted financial planner or a business valuation expert today to start building a retirement strategy that works for you.
More From Author

How to Maintain Good Personal Grooming as You Age

How to Maintain Good Personal Grooming as You Age

7 Ways to Reduce Yard Drainage Problems

7 Ways to Reduce Yard Drainage Problems

What Investors Look For Before Buying Commercial Real Estate

Commercial real estate investment presents lucrative opportunities for those who understand how to evaluate properties effectively. Successful investors do not rely on intuition alone. Instead, they conduct rigorous analysis of financial metrics, market conditions, and physical property aspects. Understanding these core evaluation principles is critical for long-term profitability.

Key Financial Metrics and Analysis

Financial performance serves as the foundation of any commercial real estate acquisition. Investors meticulously evaluate quantitative data to determine whether a property aligns with their profitability expectations and risk tolerance. This numerical analysis provides a clear, objective picture of a property’s current value and future potential and this why flexible planning matters. 

Net Operating Income

Net Operating Income represents the total revenue generated by a property minus all operating expenses. This metric excludes debt service and income taxes, providing a pure look at the property’s operational efficiency. Investors scrutinize rent rolls, ancillary income streams, and historical operating expenses to project future income accurately. A stable or growing net operating income is a strong indicator of a healthy, well-managed commercial asset.

Capitalization Rate

The capitalization rate, commonly known as the cap rate, is calculated by dividing the property’s net operating income by its current market value or purchase price. This percentage represents the expected rate of return on an all-cash investment.

Investors use cap rates to compare different properties across various markets. A lower cap rate typically indicates a higher-value property with lower perceived risk, while a higher cap rate often signals higher risk but potentially greater returns.

Cash-on-Cash Return

While the cap rate assumes an all-cash purchase, most commercial real estate transactions involve leverage. The cash-on-cash return measures the annual pre-tax cash flow divided by the actual amount of initial cash invested. This metric is crucial for investors who use financing, as it reveals the exact yield they will receive on their out-of-pocket capital during the first year of ownership.

Market Analysis and Location Dynamics

Market Analysis and Location Dynamics

A property cannot be evaluated in a vacuum. Its success is intrinsically tied to the surrounding environment. Investors conduct comprehensive market analyses to ensure the asset is situated in an area poised for sustained economic stability and growth.

Local Economic Indicators

Smart investors study the macroeconomic health of the surrounding city or region. They look for diverse local economies rather than those dependent on a single industry. High employment rates, robust job creation, and substantial infrastructure investments all signal a thriving local economy.

An area experiencing positive economic momentum will naturally drive demand for commercial spaces, whether they are retail centers, office buildings, or industrial warehouses.

Demographics and Growth Trends

Understanding the local population is vital. Investors analyze population growth, average age, education levels, and household income. For retail properties, a growing population with high disposable income is highly desirable.

For industrial properties, proximity to a dense population center might be necessary for final-mile delivery logistics. Tracking demographic shifts allows investors to anticipate future demand and adjust their property utilization accordingly.

Property Location and Accessibility

The age-old adage of “location, location, location” holds in commercial real estate. Investors look at a property’s visibility from major roadways, ease of access, and proximity to public transportation.

A property located on a busy corner with clear ingress and egress will command higher rents and attract higher-quality tenants than a similar building tucked away in an inaccessible industrial park.

Property Due Diligence and Risk Assessment

Property Due Diligence and Risk Assessment

Before finalizing a transaction, investors must uncover any hidden physical, legal, or environmental liabilities. Comprehensive due diligence protects capital and prevents unexpected financial burdens down the road.

Physical Condition and Inspections

Investors deploy teams of specialists to examine the structural integrity and mechanical systems of a building. This includes inspecting the roof, HVAC systems, plumbing, and electrical foundations. Knowing the remaining useful life of these systems allows investors to accurately budget for future capital expenditures.

Whether consulting a structural engineer or a commercial appraiser in Utah, investors rely on local experts to determine the true physical state of the asset.

Environmental Considerations

Environmental liabilities can be financially devastating. Phase I Environmental Site Assessments are standard practice in commercial real estate. These assessments research the historical use of the property to identify potential soil or groundwater contamination.

If a Phase I assessment raises red flags, a Phase II assessment involving physical soil testing is conducted. Investors will rarely proceed with a purchase if significant environmental remediation is required, unless the purchase price is adjusted to reflect those immense costs.

Legal and Regulatory Framework

Zoning laws and land-use regulations dictate what can and cannot be done with a property. Investors must confirm that their intended use for the building complies with local zoning codes. Additionally, they review title reports to uncover any easements, encroachments, or liens that could restrict property usage or cloud ownership rights.

Lease Agreements and Tenant Quality

Lease Agreements and Tenant Quality

In commercial real estate, the value of a property is heavily dependent on the quality of its tenants and the strength of its leases. Investors spend significant time reviewing existing tenant agreements.

Lease Structures and Terms

Investors analyze the specific structure of the leases in place. Triple Net leases, where the tenant is responsible for property taxes, insurance, and maintenance, are often favored by investors seeking passive income. Conversely, gross leases place the burden of operating expenses on the landlord.

The remaining duration of the leases is also critical; properties with long-term leases locked in offer immediate stability, whereas properties with expiring leases present both a risk of vacancy and an opportunity to raise rents to market rates.

Tenant Creditworthiness

A lease is only as strong as the tenant’s ability to pay. Investors scrutinize the financial health of the businesses occupying the property. National tenants with strong corporate guarantees offer immense security, whereas local, independent operators might present a higher risk of default during an economic downturn.

Vacancy Rates and Turnover

Historical vacancy rates provide insight into the property’s desirability. High turnover or prolonged periods of vacancy often indicate underlying issues with property management, location, or building condition.

Investors prefer properties with a history of high occupancy and strong tenant retention, as finding new tenants requires significant capital for leasing commissions and tenant improvements.

Financing and Investment Strategy

Finally, the acquisition must align with the investor’s broader portfolio strategy and financing capabilities. The capital stack and the long-term plan for the asset dictate the ultimate success of the venture.

Debt vs. Equity Financing

Investors must decide how to fund the acquisition. They evaluate current interest rates, loan-to-value requirements, and amortization schedules. Securing favorable commercial debt increases the cash-on-cash return, but over-leveraging a property can lead to foreclosure if tenant income drops unexpectedly. Finding the optimal balance between debt and equity is a fundamental step in the acquisition process.

Investment Horizons and Exit Strategies

Every seasoned investor enters a deal with a clear exit strategy. Some investors seek steady, long-term cash flow and plan to hold the property indefinitely for retirement benefits.

Others employ value-add strategies, planning to renovate the property, increase rents, and sell the asset for a substantial profit within five years. Defining this strategy upfront dictates how the property will be managed and financed throughout the holding period.

Conclusion

Purchasing commercial property requires careful consideration of numerous variables, from detailed financial metrics to comprehensive physical inspections.

By systematically evaluating market conditions, tenant quality, and overall risk, investors position themselves for sustained financial success. Strategic preparation remains the ultimate key to building a resilient portfolio.

More From Author

What Makes Employees Stay Longer at Companies

What Makes Employees Stay Longer at Companies

Neon Lights and Night Owls: Why More People Explore the City After Dark

Neon Lights and Night Owls: Why More People Explore the City After Dark

Fixed vs Variable Auto Loans: Which Is Better?

Choosing the right auto loan can significantly impact your monthly budget and overall financial health. When financing a vehicle, borrowers typically choose between fixed and variable auto loans. Each option has its benefits and risks, and the right choice depends on your financial goals, income stability, and comfort with change.

This guide outlines the key differences between fixed and variable auto loans to help you make an informed decision when exploring your financing options.

What is a fixed auto loan?

A fixed auto loan has an interest rate that remains the same for the life of the loan. This means your monthly payment is predictable and won’t change, from the first payment to the last.

Key benefits of fixed auto loans: A major advantage of a fixed loan is stability . Because you know exactly how much you owe each month, budgeting is simpler and less stressful. This predictability is particularly useful for households that need consistent monthly planning.

Fixed loans also shield borrowers from market fluctuations; even if interest rates rise, your loan rate is locked in. This security appeals to buyers who value long-term certainty over potential short-term savings.

When a fixed loan makes sense: Fixed loans are ideal if you plan to keep your vehicle for several years or prefer predictable expenses. This option also suits first-time buyers who value clarity and simplicity throughout the life of the loan.

What is a variable auto loan?

What is a variable auto loan

A variable auto loan has an interest rate that fluctuates with market conditions. These changes can increase or decrease your monthly payments, depending on rate movements.

  • Key benefits of variable auto loans: Variable loans often begin with lower interest rates than fixed loans, leading to lower initial payments and potential savings if market rates remain stable or drop. They also offer more flexibility; borrowers who expect their income to grow or plan to pay off the debt early can benefit significantly from these lower starting rates.
  • When a variable loan makes sense: Variable auto loans are best for borrowers comfortable with fluctuating rates. If you have the financial cushion to handle potential payment increases, this option can provide significant short-term savings.

Comparing fixed and variable auto loans

Payment stability vs flexibility: Fixed loans provide consistent payments, making them easier to manage long-term. Variable loans offer flexibility but require closer monitoring of interest rate changes.

Risk and predictability: With a fixed loan, there is little financial risk tied to rate changes. Variable loans carry more uncertainty, as payments may increase unexpectedly.

Long-term cost considerations: While variable loans may start cheaper, a rise in interest rates can result in higher overall costs. Fixed loans may have slightly higher initial rates, but they often provide peace of mind over time.

How your financial situation impacts your choice: Your personal financial situation is a key factor in choosing between fixed and variable loans. Consider your income stability, existing debt, and future financial goals.

Borrowers with a steady income who plan to keep their vehicle for the long term often prefer the security of a fixed loan. Conversely, those with a higher risk tolerance or plans to sell or refinance quickly may benefit from a variable loan.

Lifestyle factors, such as commuting habits and vehicle longevity, also impact how long you’ll hold the loan. Many buyers researching auto loans in Utah carefully weigh these personal variables before making a commitment.

Interest rates and market conditions: Economic conditions greatly impact the performance of variable loans. When interest rates are low and stable, variable loans can be appealing. However, during times of rising or unpredictable rates, fixed loans often provide more security. Staying informed about rate trends and understanding how adjustments work can help borrowers avoid unexpected costs.

Making the right decision for your needs

Making the right decision for your needs

When it comes to auto loans, there’s no one-size-fits-all solution. The best choice depends on your tolerance for risk and preference for payment stability. Fixed loans provide simplicity and consistent payments, while variable loans offer potential savings with greater risk in banking industry.

Consider your financial habits, future goals, and comfort with uncertainty to determine the right option for you.
Conclusion

Knowing the difference between fixed and variable auto loans helps you make better financing choices. By comparing options, evaluating your budget, and considering the long-term impact, you can choose a loan that supports your financial health instead of straining it.
Taking a thoughtful approach to auto financing can make owning a vehicle simpler and less stressful, no matter which loan type you select.

More From Author

Your Garden as a Mirror How It Reflects Your Personality

Your Garden as a Mirror: How It Reflects Your Personality

Office Layout Mistakes to Avoid for a Happier Workplace

Office Layout Mistakes to Avoid for a Happier Workplace

How Can the 50/30/20 Rule Help You Achieve Your Financial Goals?

Are you looking to finally take control of your finances? The 50/30/20 rule is a simple yet powerful budgeting technique that can help you manage your money, save effectively, and achieve your financial goals. Whether you’re a budgeting beginner or an experienced saver, understanding this rule can completely change the way you approach your finances.

By breaking down your income into clear categories, you can prioritize essential needs, set aside funds for personal wants, and build a solid savings plan for your future. Get ready to transform your financial habits and pave the way for long-term financial success!

What is the 50/30/20 Rule?

The 50/30/20 rule is a straightforward way to allocate your income into three categories:

  • 50% for Needs – These are essential expenses you can’t live without.
  • 30% for Wants – Non-essential items that improve your quality of life.
  • 20% for Savings – This portion is for your future and financial growth.

This rule is designed to help you balance your immediate needs with long-term financial health, making budgeting simple and achievable. Whether you’re trying to get out of debt, start building an emergency fund, or save for retirement, the 50/30/20 rule provides a solid foundation for your financial strategy. 

Additionally, if you’re working toward bigger financial goals like buying a house, this rule can help you allocate the right funds for a down payment or manage your finances wisely if you plan to buy a house without a realtor, saving you on commission fees.

How to Implement the 50/30/20 Rule

How to Implement the 50-30-20 Rule

Step 1: Calculate Your Income

The first step to using the 50/30/20 rule is calculating your after-tax income. This is the amount you bring home after all taxes and deductions. For many people, this will be your monthly salary or the total monthly income from various sources.

Step 2: Allocate Your Budget

Once you know your income, it’s time to break it down:

  • 50% for Needs: These include things like rent/mortgage, utilities, groceries, and transportation. Basically, all the expenses you can’t live without.
  • 30% for Wants: This covers things like dining out, entertainment, subscriptions, and vacations. While these aren’t essential, they are things that improve your lifestyle.
  • 20% for Savings: This includes contributions to your retirement account, building an emergency fund, or any other savings goals you may have.

Step 3: Track and Adjust

The 50/30/20 rule is a guideline, not a strict rule. It’s important to track your spending each month and make adjustments based on your actual needs and lifestyle. For example, if you’re living in a high-cost area, you might need to allocate more to “needs” and less to “wants.” 

Similarly, if you’re aggressively saving for a down payment, you might want to put more toward savings temporarily.

Why the 50/30/20 Rule Works for Most People

Why the 50-30-20 Rule Works for Most People

The 50/30/20 rule is so effective because it’s both flexible and simple. It doesn’t require complex calculations or restrictive financial habits. Instead, it allows you to prioritize your ordinary and necessary expenses, indulge in the things you love, and still make progress on your savings.

It’s perfect for people at any financial level because it:

  • Provides a clear structure for your budget.
  • Is easy to stick to and doesn’t feel too restrictive.
  • Helps you prioritize savings without sacrificing too much lifestyle enjoyment.

Adjusting the 50/30/20 Rule for Your Unique Needs

Adjusting the 50-30-20 Rule for Your Unique Needs

While the 50/30/20 rule works for many people, it’s important to adjust it based on your unique situation. Here are a few ways to modify the rule:

For High-Debt Individuals:

If you’re dealing with significant debt, consider shifting more of your budget to the 20% savings category by temporarily reducing your “wants” category. You can always adjust later as you pay down your debt.

For High-Income Earners:

For those making a higher income, you might find that the 50% for needs category becomes less significant. In this case, you can allocate more to savings and investments to accelerate your wealth-building.

For Single Parents or Families:

Family expenses can often exceed the 50% needs category. In this case, adjusting your “wants” category to fit your needs is essential.

Frequently Asked Questions

1. Can the 50/30/20 rule be applied if my income fluctuates?

Yes! If your income is variable, such as from freelancing or commission-based work, use an average of your monthly income over the past few months to calculate your budget.

2. Should I consider savings for retirement part of my 20% savings?

Yes! Your retirement savings, emergency fund, and any other savings goals should come from the 20% of your income allocated for savings.

3. How can I stick to the 50/30/20 rule if my living expenses are high?

If you live in a high-cost area, it’s okay to adjust the allocation. You might need to allocate 60% to needs and reduce the “wants” category temporarily. Just make sure you’re still saving something.

4. What should I do if I can’t meet the 20% savings goal?

If saving 20% is challenging, start with a smaller amount and work your way up. Even 10% is a good start. The key is consistency and gradually increasing your savings over time.

Final Thoughts

The 50/30/20 rule is a simple, adaptable budgeting strategy that can help you take control of your finances in 2025. By breaking down your income into manageable categories, you can ensure that your essential needs are covered, your wants are fulfilled, and your savings continue to grow.

With consistent tracking and small adjustments, this rule can help you find the right balance between living in the moment and planning for your future. Start implementing the 50/30/20 rule today, and take the first step towards a more financially secure life.

More From Author

The Role of Knee Braces in Osteoarthritis Management

Enhancing Mobility: The Role of Knee Braces in Osteoarthritis Management

From Power to Robotics - The Exciting Subfields of Electrical Engineering

From Power to Robotics: The Exciting Subfields of Electrical Engineering

Best Tech News Feedcryptobuzz: How I Decide What’s Worth My Time in a Noisy Tech World

As someone who has spent over a decade studying property markets, I’ve learned one habit that never fails me: filter the noise before it touches my decisions. Whether I’m tracking housing data, interest rates, or broader economic shifts, the quality of my information matters. That’s why the search term best tech news feedcryptobuzz caught my attention.

Tech and crypto news shape markets, investor sentiment, and even real estate trends. But not every platform deserves equal trust. I read widely, compare sources daily, and I stay practical about what actually helps me make smarter decisions. Here’s how I look at Feedcryptobuzz—and how you should too.

Is Best Tech News Feedcryptobuzz a Reliable Daily Read?

Is Best Tech News Feedcryptobuzz a Reliable Daily Read?

When people search for best tech news feedcryptobuzz, they’re usually looking for one simple thing: a reliable place to stay updated without drowning in jargon. Feedcryptobuzz positions itself as an emerging hub for tech and crypto insights, and I understand the appeal. It promises fast updates, trending topics, and simplified explanations.

From my routine, I see Feedcryptobuzz as a discovery tool, not a decision-making authority. It works best for scanning headlines or spotting what people are talking about. Where it struggles is depth. I rarely see clear author credentials, transparent sourcing, or long-term accountability. In markets—and in tech—that matters.

If you rely on it alone, you risk missing context. I always cross-check anything important with established outlets before I act on it.

How Does Feedcryptobuzz Compare to Established Tech News Sources?

I treat tech news the same way I treat property data. One source never tells the full story. Here’s how Feedcryptobuzz stacks up against outlets I use weekly.

Platform Best For Why I Trust It
Feedcryptobuzz Trend scanning Quick exposure to topics
TechCrunch Startups & VC Strong reporting standards
Wired Tech + society Deep analysis and context
The Verge Consumer tech Balanced reviews and culture
Ars Technica Technical depth Expert-level explanations

Feedcryptobuzz feels lighter and faster, which works for casual reading. But when I want to understand how AI, cybersecurity, or infrastructure trends affect markets and investment behavior, I lean on sources with proven editorial discipline.

Why Does Tech News Quality Matter for Financial Decisions?

Why Does Tech News Quality Matter for Financial Decisions?

This is where my property background kicks in. Tech trends don’t exist in isolation. AI adoption affects labor markets. Cybersecurity risks influence insurance and commercial property costs. Data infrastructure impacts where companies choose to expand.

When tech news lacks verification, it creates false confidence. I’ve seen investors chase narratives that collapse under scrutiny. That’s why I treat Feedcryptobuzz as contextual background, not a primary signal.

High-quality tech journalism helps you connect dots between innovation, regulation, and long-term value. That connection directly influences how I advise buyers and investors at Insight Realty Network.

What Tech Trends Should You Actually Watch Going Into 2026?

What Tech Trends Should You Actually Watch Going Into 2026?

Not every headline deserves your attention. I focus on trends with real-world consequences.

Artificial intelligence now drives business operations, not experiments. Agentic AI systems will reshape workflows and decision-making speed. Physical AI and robotics will influence logistics, construction, and service industries—areas that directly affect property demand.

Infrastructure shifts matter too. Hybrid cloud and AI supercomputing change where data centers operate and how energy gets priced. Cybersecurity and digital provenance influence trust, compliance, and risk modeling. These trends rarely get full treatment on lighter platforms like Feedcryptobuzz, which is why I pair it with deeper reporting.

Can Feedcryptobuzz Fit Into a Smarter News Routine?

Can Feedcryptobuzz Fit Into a Smarter News Routine?

Yes—if you use it intentionally. My daily routine looks like this:

I skim lighter feeds early in the morning to spot themes. Feedcryptobuzz fits here. Then I move to established outlets for confirmation and depth. By the time I make decisions or share insights with clients, I rely only on verified reporting.

Think of Feedcryptobuzz as the appetizer, not the main course. It can point you toward topics worth exploring, but it shouldn’t be the final word—especially if money, privacy, or long-term planning is involved.

Should You Trust “Best” Claims in Tech News Rankings?

Any platform calling itself the “best” deserves skepticism. I apply the same rule in real estate rankings. I ask simple questions: Who wrote this? What data supports it? What incentives sit behind the content?

The phrase best tech news feedcryptobuzz works as a search term, but “best” depends on what you need. If speed and simplicity matter, it may work. If accuracy, accountability, and depth matter, you need more established sources in your mix.

Smart readers build ecosystems, not loyalties.

FAQs

1. Is Feedcryptobuzz safe to use for tech and crypto news?

Feedcryptobuzz is generally safe for casual browsing, but I don’t treat it as a sole source. It lacks visible editorial standards and verified authorship, which means I always cross-check important claims. For major decisions or market insights, I rely on established tech and crypto publications with transparent sourcing.

2. Why do professionals avoid relying on one tech news source?

Markets reward context, not speed alone. Professionals avoid single-source news because it increases bias and blind spots. I use multiple outlets to verify trends, understand opposing views, and reduce misinformation. This habit applies equally to tech, finance, and real estate.

3. Can lighter tech news platforms still be useful?

Absolutely. Lighter platforms help surface trends quickly. I use them to stay aware of conversations and emerging topics. Their value increases when paired with deeper analysis from reputable sources that provide data, accountability, and long-term perspective.

4. What’s the best way to stay informed without information overload?

Create a routine. Use one or two fast-scanning platforms, one deep-analysis source, and one curated newsletter. This balance keeps you informed without burning time or attention. Consistency matters more than volume.

So, Here’s My No-Nonsense Take Before You Refresh That Feed

If you’re searching for best tech news feedcryptobuzz, use it—but don’t stop there. Treat it like background music while you prep for the real work. The decisions that shape your financial future deserve information with weight behind it.

My rule stays simple: scan wide, verify deep, act carefully. That habit has served me well in property markets, and it works just as well in tech.

And if you ever feel overwhelmed by headlines, step back. The smartest move sometimes is choosing what not to read.

More From Author

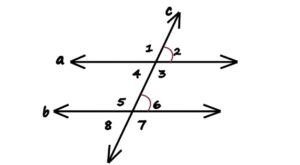
which diagram shows lines that must be parallel lines cut by a transversal?

Which Diagram Shows Lines That Must Be Parallel Lines Cut by a Transversal?

dreamwithjeff com

dreamwithjeff com: What This Viral Project Teaches Us About Focus, Creativity, and Modern Goal Thinking

Real Estate vs Stock Market: Which Investment Will Make You More Money?

Are you torn between real estate and the stock market for your next investment? Both options are popular and offer unique benefits, but they come with distinct advantages and risks. Real estate provides a tangible asset with the potential for steady cash flow and long-term appreciation. 

In contrast, the stock market offers high liquidity and the possibility of rapid growth, but it also comes with increased volatility. The real question is: which one aligns better with your financial goals, risk tolerance, and timeline? Let’s break down the key differences between these two investment options to help you make an informed decision.

What is Real Estate Investing?

Key Differences Between Real Estate and Stock Market Investments

Real estate investing involves purchasing, managing, or selling properties to generate income or profit. Real estate is a tangible asset, which provides both long-term growth through appreciation and passive income via rental properties. It’s often considered a more stable investment compared to stocks.

Advantages of Real Estate Investing:

  • Steady Cash Flow: Rental properties offer consistent income streams.
  • Appreciation: Property values generally rise over time, building wealth.
  • Tax Benefits: Investors can take advantage of credits and deductions for individuals such as maintenance and mortgage interest.
  • Tangible Asset: Real estate provides a physical asset that can be leveraged.

Disadvantages of Real Estate Investing:

  • High Initial Investment: Real estate requires significant capital for purchasing properties.
  • Low Liquidity: Selling a property can take weeks or months, making it less liquid.
  • Maintenance Costs: Properties require upkeep, including repairs, taxes, and insurance.
  • Market Risk: Real estate values can decline due to market fluctuations, economic downturns, or local factors.
  • Tenant Issues: Managing tenants can be time-consuming and costly, especially if issues arise, such as non-payment or property damage.
  • Property Management: If you hire property managers, their fees can reduce your profits, and self-management can be labor-intensive.
  • Legal and Regulatory Risk: Changes in laws, zoning regulations, or rent control laws can impact your profitability.
  • Capital Gains Tax: When selling real estate, you may be subject to capital gains taxes on the appreciation, reducing your overall profit.

What is Stock Market Investing?

What is Stock Market Investing

Stock market investing involves buying shares of publicly traded companies. The goal is to earn returns from dividends and capital gains as the value of your stocks grows. Stocks are considered more liquid than real estate, and the stock market offers high growth potential but comes with increased volatility.

Advantages of Stock Market Investing:

  • Liquidity: Stocks can be bought and sold almost instantly.
  • Lower Entry Costs: You can start investing with a smaller amount of capital.
  • Higher Growth Potential: Historically, stocks have outperformed real estate in terms of long-term growth.
  • Diversification: The stock market offers a variety of investment options across multiple industries.

Disadvantages of Stock Market Investing:

  • Volatility: Stock prices can fluctuate significantly, especially in the short term.
  • Market Risk: Economic conditions, company performance, and other external factors can impact stock prices.
  • Emotional Stress: The ups and downs of the stock market can cause stress for investors, particularly those with short-term goals.
  • Lack of Control: As a stock investor, you have no control over the companies you invest in, and you must rely on their performance and external market forces.
  • Tech News Feedcryptobuzz Influence: The influence of social media, tech news, and cryptocurrency updates can contribute to sudden market shifts, making it hard to predict trends accurately.
  • Short-Term Losses: While long-term investments typically perform well, short-term fluctuations can cause significant losses, especially during market crashes or corrections.
  • Brokerage Fees: Buying and selling stocks often involves brokerage fees, which can eat into profits over time.

Key Differences Between Real Estate and Stock Market Investments

Key Differences Between Real Estate and Stock Market Investments

1. Returns on Investment (ROI)

Both real estate and the stock market offer returns, but in different forms. Real estate tends to provide steady, long-term returns through rental income and appreciation. Stocks, on the other hand, offer higher growth potential but are more susceptible to volatility, making them riskier in the short term.

2. Risk Level

When comparing real estate vs. stock market, real estate is generally seen as a safer investment. Properties appreciate over time and provide more stability. Stocks, however, are more volatile and can experience significant fluctuations, depending on the market and economic conditions.

3. Liquidity

Stock market investments are far more liquid than real estate. You can buy and sell stocks within minutes, while real estate transactions can take months, making it harder to access your capital quickly.

4. Management and Maintenance

Real estate investing requires more active involvement, whether it’s maintaining property, managing tenants, or dealing with taxes. In contrast, stock market investments are more passive, as you don’t have to manage or maintain shares once purchased.

Frequently Asked Questions

1. Which is better: real estate or the stock market?

It depends on your investment goals. Real estate is great for long-term stability and predictable returns, while the stock market offers higher returns but with more volatility.

2. Can you lose money in real estate?

Yes, real estate can lose value if the property market drops, or if maintenance and management costs exceed rental income. However, real estate tends to be less volatile than stocks.

3. What’s more profitable: real estate or stocks?

Both offer profitable opportunities, but real estate generally provides more stable cash flow through rental income, while stocks tend to provide higher growth potential, especially in the long run.

4. How much money do I need to start investing in real estate?

Typically, you’ll need at least 20% down for most properties. However, you can also consider REITs (Real Estate Investment Trusts), which allow for lower capital investment and diversification.

5. How do I reduce risk when investing in stocks?

To reduce risk, diversify your portfolio, focus on long-term investments, and choose stocks from stable, established companies. Avoid reacting to short-term market changes.

Final Thoughts

The difference between real estate and stock market investments boils down to your personal financial goals, risk tolerance, and investment timeline. If you’re looking for stability, passive income, and tangible assets, real estate might be the better option. If you’re after liquidity, higher returns, and a more hands-off approach, then the stock market could be the right fit.

Many investors find success by diversifying, incorporating both real estate and stocks in their portfolios to balance risk and maximize returns. Ultimately, the best choice depends on your individual circumstances and financial objectives.

More From Author

What to Do When You Need Emergency Dental Care in Falls Church

What to Do When You Need Emergency Dental Care in Falls Church

Benefits Of Dental Implants For Long-Term Oral Health

Benefits Of Dental Implants For Long-Term Oral Health

Personal Property Coverage for a Mobile Home Is: What It Actually Covers (and What It Doesn’t)

If you own or live in a manufactured home, understanding personal property coverage for a mobile home is the difference between a smooth claim and a painful out-of-pocket bill. In most policies, this protection (often called “Coverage C”) pays to repair or replace your belongings—furniture, clothing, electronics—when they’re damaged, destroyed, or stolen due to a covered peril.

What does personal property coverage include for manufactured homes?

At its core, Coverage C protects your stuff—not the structure. Think furniture, appliances you own, clothing, small electronics, and décor. If a named peril like fire, wind, hail, or theft strikes, the policy helps pay for replacements up to your coverage limit, minus your deductible. Many manufactured‐home policies mirror standard homeowners coverage but are tailored to mobile/manufactured risks.

Coverage typically follows your belongings on or off premises—for example a laptop stolen from your car may still be covered (often with a lower off‐premises sublimit). Always check your declarations page for limits and sublimits on categories like jewelry, collectibles, or cash.

What does personal property coverage include for manufactured homes

How do insurers value your belongings: ACV vs. Replacement Cost?

One of the biggest claim surprises is how items are valued. With Actual Cash Value (ACV) the insurer pays the cost to replace your item minus depreciation (wear and tear). With Replacement Cost (RCV) depreciation is not deducted—you get what it costs to buy a new, similar item today. Manufactured‐home policies often start with ACV unless you add an RCV endorsement. Choosing RCV usually costs more but can significantly reduce your out‐of‐pocket at claim time.

Which perils are typically covered—and which are not?

Most mobile home policies cover common risks: fire, wind/hail, explosion, theft, vandalism, and certain types of water damage (not flood). Flood and earthquake are almost always excluded and require separate policies or endorsements. Review your policy’s named perils and exclusions carefully; coverage can vary by insurer and state.

Tip: If you want broader protection for belongings (fewer “named peril” gaps), ask whether your carrier offers a more comprehensive form or endorsement that expands personal property protection and confirm how it applies to manufactured homes in your state.

How much personal property coverage do you need?

A fast rule of thumb is to complete a room-by-room home inventory—photos + receipts if possible—then total the replacement value. Many regulators and consumer guides emphasise that deductibles apply to personal property claims and that higher deductibles reduce premiums, but you’ll pay more out‐of-pocket per claim. Keep your limits aligned with what it would cost to replace your belongings today, not what you originally paid.

Some insurers and state regulators specifically call out personal property coverage in manufactured home policies—use their checklists and free inventory apps to document your items before a loss.

Are there special limits on certain items?

Yes. Categories like jewelry, watches, firearms, silverware, collectibles, musical instruments, and cash often have sublimits (e.g., a few thousand dollars for theft), regardless of your overall Coverage C limit. If you own high-value pieces, consider scheduling them (itemising with appraisals) or adding appropriate floaters to raise protection.

Does coverage follow my stuff when I travel or move?

Generally, your personal property is covered off-premises worldwide, but often at a reduced percentage of your on‐premises limit. Moving can be tricky—damage in transit may be limited or excluded. Confirm with your insurer how off-premises and in-transit coverage applies to your specific manufactured home policy.

Does coverage follow my stuff when I travel or move

How it differs from homeowners insurance

Although the aim is similar, the way personal property coverage for a mobile home works differs from a standard homeowners policy in several key ways. A policy designed for manufactured homes takes into account their particular characteristics—such as transportation, anchoring, foundation type, and increased vulnerability to weather events. Because of this, many insurers will not offer a conventional homeowners policy like the widely used HO-3 for a mobile home dwelling. 

Instead, one must secure a policy specifically suited to factory-built or mobile/manufactured homes—commonly labelled HO-7 (or similar) in many states. These specialized policies reflect the unique risks and underwriting criteria of mobile home living and differ in structure, eligibility, and cost from typical homeowners policies.

What else should mobile home owners know?

Manufactured home insurance is built around two big buckets: physical damage (dwelling and contents) and personal liability. Your additional living expenses/loss of use coverage may also help with hotel or rental costs if a covered loss makes your home uninhabitable—another reason to right-size your limits.

What else should mobile home owners know

Frequently Asked Questions

1. Is personal property coverage for a mobile home the same as homeowners Coverage C?

Functionally, yes—it protects your belongings against covered perils. The big difference is in policy form & underwriting tailored to manufactured homes. Coverage terms (named perils vs broader form), limits, and endorsements can differ by carrier and state, so confirm specifics with your insurer and read the declarations and exclusions closely.

2. Should I choose replacement cost or ACV for my mobile home contents?

If budget allows, replacement cost is the safer bet because it does not subtract depreciation at claim time, helping you buy new equivalents after a loss. ACV is cheaper but often yields smaller payouts. Ask your carrier if an RCV endorsement for contents is available for your manufactured home policy.

3. Are floods, earthquakes and mold covered for my personal property?

Flood and earthquake are typically excluded from standard policies; you’d need separate coverage (e.g., NFIP flood policy) or endorsements where available. Mold coverage is often limited or subject to strict conditions and caps. Always verify exclusions and available add‐ons before you need them.

4. How much personal property coverage should I carry?

Build a home inventory and aim for a limit that reflects the current replacement cost of your belongings. Remember that higher deductibles lower premiums but increase your share per claim, and that sublimits apply to certain categories (e.g., jewelry). Revisit limits annually or after big purchases.

So, what personal property coverage for a mobile home is — in one line

It’s the part of your manufactured home policy that replaces your belongings after a covered loss, ideally at replacement cost, with the right limits, documented inventory, and endorsements for high-value items. Start by confirming ACV vs RCV, checking sublimits, and aligning your limit with what it takes to fully replace your stuff today.

More From Author

Why Might People Choose to Rent a Home Rather Than Buy a Home

Why Might People Choose to Rent a Home Rather Than Buy a Home?

electrical wire connectors types

Electrical Wire Connectors Types: My Hands-On Guide to Getting It Right

How Much Is a Double Wide Trailer? A Real-World 2025 Buyer’s Guide

I’ve walked plenty of lots, toured model homes that smelled like fresh lumber, and crunched more spreadsheets than I care to admit. So let’s get straight to what you came for: how much is a double wide trailer right now—and what you’ll actually spend by the time you’re moved in.

How much is a double wide trailer in 2025?

How much is a double wide trailer in 2025?

The U.S. Census Bureau’s Manufactured Housing Survey puts the average sales price of a new double-section (double-wide) manufactured home at about $152,900 as of April 2025 (home only, land excluded). 

Round it to a practical range and you’ll typically see $140,000–$170,000 for many standard double-wides before upgrades and local add-ons. Industry and consumer guides commonly cite similar ballparks (often $145,000–$160,000 as an “average”), which aligns with the federal data trend. 

Quick reality check: list prices on dealer lots can come in lower or higher depending on brand, size, and features. Always compare spec-for-spec.

What drives the price of a double-wide?

Square footage & layout: Most double-wides run ~1,000–2,200+ sq. ft.; more space and more sections mean more materials and higher transport/setup costs. 

Build & finishes: Energy-efficient windows, drywall versus paneling, upgraded insulation, pitched roofs, luxury vinyl plank, and appliance packages all move the needle. Per-square-foot figures for manufactured homes often land roughly $40–$85/sq. ft. before location factors. 

Regional market & availability: Freight distances, factory capacity, and local labor rates matter. 2024–2025 price trends also reflect material and freight variability tracked by the Census data series. 

What other costs should I expect beyond the home price?

What other costs should I expect beyond the home price?

Delivery & setup: Expect transport and basic installation to add several thousand dollars. Guides typically estimate $1,500–$5,000 for basic setup, with complex sites costing more.

Foundation, skirting, and steps/porches: HUD-code homes still need an approved foundation or support system; permanent foundations, skirting, and porches can add meaningfully to your budget.

Utilities & site prep: Budget for grading, utility tie-ins (water, sewer/septic, electric, gas), driveway, and permits. If you’re moving an existing home or relocating after purchase, professional estimates for moving a manufactured home often run $3,500–$18,000 depending on distance, size, and whether setup is included; double-wides trend toward the higher portion of that range. 

Upgrades & codes: Wind/snow load packages, hurricane tie-downs, and regional code options can add cost but are non-negotiable in many areas.

Is a double-wide still cheaper than site-built?

Generally, yes—especially at the price-per-square-foot level. Recent analyses show manufactured homes averaging ~$79–$87/sq. ft. (single- vs. multi-section) versus ~$169/sq. ft. for new site-built homes (excluding land).

That’s roughly half on a per-foot basis, which is why double-wides remain a value play for buyers focused on payment and space. 

What smart financing options exist for double-wides?

If the home will be placed on a permanent foundation on owned land and meets guidelines, some buyers can use traditional mortgages; otherwise, chattel loans are common for home-only purchases.

One large retail lender notes minimum down payments around 5% for eligible manufactured-home mortgages (criteria apply), with setup costs and site work considered separately.

Pro tip: lock down the total project scope before you apply—home, options, delivery, setup, foundation, and site work—so your loan amount actually covers what you plan to do.

FAQs: Straight answers to common questions

  • What’s the most accurate “average” price for a double-wide today?

If you want a neutral benchmark, use federal data: $152,900 (April 2025) for new double-section homes—home only, no land. Actual invoices vary with options and region, but that figure gives you a solid anchor for negotiations.

  • Does “how much is a double wide trailer” include land?

No. Almost all averages you see—especially the federal numbers—are home-only prices. Land (or a long-term lease), foundation, utilities, and permits are separate line items you must budget for. 

  • How much does delivery and setup usually add?

Basic setup can start in the low thousands and scale with site complexity. Third-party estimates and lender guides commonly cite $1,500–$5,000 for basic setup, but long distances, cranes, and complex foundations can push higher. 

  • Is now still a good time to buy a double-wide?

If payment and square footage matter, double-wides remain compelling versus site-built on a per-foot basis. Use the federal average and local comps to negotiate—and plan thoroughly for site costs so you don’t blow the budget in the last mile. 

The bottom line: How much is a double wide trailer—really?

On paper, it’s about $150K on average (home only). In practice, your all-in number depends on features, setup, and site work.

Anchor your expectations with the latest Census average, compare dealer quotes apples-to-apples, and price the “invisible” costs—foundation, utilities, and permits—before you sign.

If you want, I can turn this into a quick budgeting worksheet with line-item ranges so you can plug in quotes and see your total project cost versus payment targets. Meanwhile, keep this cheat sheet handy:

  • Benchmark: ~$152.9K average (double-wide, home only). 
  • Typical market range: ~$140K–$170K before upgrades.  
  • Setup & delivery: plan a few thousand more (basic) and scale up for complex sites.  
  • All-in reality: land + foundation + utilities + permits can rival (or exceed) the home line—budget early to avoid surprises. 

More From Author

how much is vinyl siding for a 1,500 sq ft house

How Much Is Vinyl Siding for a 1500 sq ft House?

what happens if you inherit a house with a reverse mortgage

What Happens If You Inherit a House with a Reverse Mortgage? A Clear Guide for Heirs

How to Buy a House Without a Realtor: Your 2025 Step-by-Step Guide

I’ll be honest — the first time I considered how to buy a house without a realtor, I was both excited and intimidated. The idea of saving thousands in commissions sounded amazing, but the thought of handling contracts, inspections, and negotiations on my own?

Terrifying. Still, I learned that buying a home solo is not only possible — it’s absolutely doable if you know what to expect and prepare ahead of time. Here’s everything you need to know to pull it off confidently in 2025.

Can You Legally Buy a House Without a Realtor in 2025?

Can You Legally Buy a House Without a Realtor in 2025?

Yes, you absolutely can. There’s no law requiring you to hire a real estate agent. Many buyers go this route, especially when purchasing homes listed “For Sale By Owner” (FSBO). These deals are often simpler and may save you money on commission costs.

However, a big change since August 17, 2024, affects how commissions work. Due to a major National Association of Realtors (NAR) settlement, buyer’s agents must now have a signed agreement before showing homes. If you’re not using an agent, you won’t need that agreement — but it’s good to know how the landscape is shifting.

Step 1: Secure Financing and Plan Your Budget

Before you fall in love with any home, get preapproved for a mortgage. This tells you how much you can borrow and shows sellers you’re serious. Compare lenders carefully — even a small difference in interest rates can save you thousands over the life of the loan.

But financing is only part of the equation. You’ll also need to budget beyond the purchase price. Factor in closing costs (typically 2%–5% of the loan amount), inspection fees, appraisal fees, moving expenses, and potential repairs. Building these into your budget early keeps your finances stress-free later.

Step 2: Find and Evaluate Properties on Your Own

Without an agent, you’ll be doing the legwork yourself — but that doesn’t mean it’s hard.

Look for FSBO listings: These are homes sold directly by the owner, often advertised on FSBO-specific websites, major listing platforms, or even yard signs in neighborhoods.

Research the market: Study recent comparable sales (“comps”) in the same area to understand fair pricing. Sites like Zillow, Redfin, and local property records are great resources.

Evaluate the neighborhood: Since you won’t have a realtor’s insights, it’s on you to research the area. Check school district ratings, crime statistics, commute times, nearby amenities, and community events.

Visit at different times of day to get a feel for traffic and noise levels. A home is more than its walls — the neighborhood can dramatically impact your quality of life and resale value.

Step 3: Make an Offer Using the Right Forms and Contingencies

Make an Offer Using the Right Forms and Contingencies

When you’re ready to make an offer, use state-approved purchase agreement forms. These forms help ensure your offer is legally sound and include all the details needed for a valid contract.

Be sure to include essential contingencies, such as:

  • Financing contingency – your offer is valid only if you secure a loan. 
  • Inspection contingency – you can renegotiate or walk away if serious issues are found. 
  • Appraisal contingency – the property must appraise for at least the purchase price. 

These clauses protect you from unexpected problems and give you leverage during negotiations.

Step 4: Negotiate Directly With the Seller

Negotiating without a realtor can feel daunting, but it’s manageable if you stay prepared. Remember, FSBO sellers are often trying to avoid paying commission, so they might not be eager to lower the price significantly. However, solid market research gives you the confidence to stand firm on fair offers.

Keep the conversation respectful and solutions-focused. If issues arise during inspection, request repairs or a price reduction instead of walking away immediately. Negotiations are about finding middle ground that works for both parties.

Step 5: Order Professional Inspections and an Appraisal

Don’t skip inspections. Hire a qualified home inspector to check the property’s structure, roof, electrical systems, plumbing, and more. Depending on the property, you might also need specialized inspections (e.g., for septic systems or radon).

Your lender will likely require a professional appraisal to confirm the home’s value. Even if you’re buying in cash, consider ordering one independently — it’s a small cost compared to the risk of overpaying.

Step 6: Hire a Real Estate Attorney

Hire a Real Estate Attorney

While not legally required everywhere, a real estate attorney can be your best safeguard. They review contracts, disclosures, and closing documents to make sure everything is compliant and in your best interest. In some states, attorney involvement is mandatory, so check your local laws early in the process.

Step 7: Hire a Title Company

A title company plays a crucial role in protecting your ownership rights. They’ll perform a title search to confirm the seller legally owns the property and that there are no liens or disputes. They also issue title insurance, which protects you from future ownership claims, and handle many of the logistics at closing.

Step 8: Close the Deal

Once inspections are complete, financing is secured, and the title is cleared, you’re ready for closing. The attorney or title company will guide you through signing all final documents, transferring funds, and recording the deed. Once everything’s complete, the keys are yours.

Frequently Asked Questions

  • Can I still tour homes without signing anything?

Yes, if you’re not using an agent, you can tour homes freely. However, if you ever decide to work with an MLS-affiliated buyer’s agent, you’ll now need a signed agreement before touring — a new rule after the 2024 NAR settlement.

  • Will I save money by buying a house without a realtor?

You might, but it depends. While you could save on commission, you’ll likely pay separately for inspections, legal help, and title services. Also, if you overpay due to poor negotiation, the savings could vanish.

  • Do I need a lawyer if I skip a realtor?

It’s not required everywhere, but highly recommended. A real estate attorney can protect your interests, spot legal issues you might miss, and ensure all documents are accurate before closing.

  • Can the seller still pay for a buyer’s agent if I hire one later?

Yes. Even with the new rules, you can negotiate for the seller to cover a buyer’s agent fee through concessions or closing credits — but this must be discussed outside of the MLS listing.

Final Word: Mastering How to Buy a House Without a Realtor

Figuring out how to buy a house without a realtor might seem overwhelming at first, but with the right knowledge and preparation, it’s completely achievable.

From securing financing and researching neighborhoods to drafting offers and hiring a title company, you’re in full control of the process.

Whether you’re buying a FSBO property or just want more independence in your home search, taking the DIY route can be empowering — and potentially cost-effective.

Just approach it with patience, research, and a solid team of professionals for the parts where expertise matters most.

More From Author

how big is 250 square feet

How Big Is 250 Square Feet? Visualizing and Using Small Spaces

how big is 400 square feet

How Big Is 400 Square Feet? A Practical Guide You Can Picture